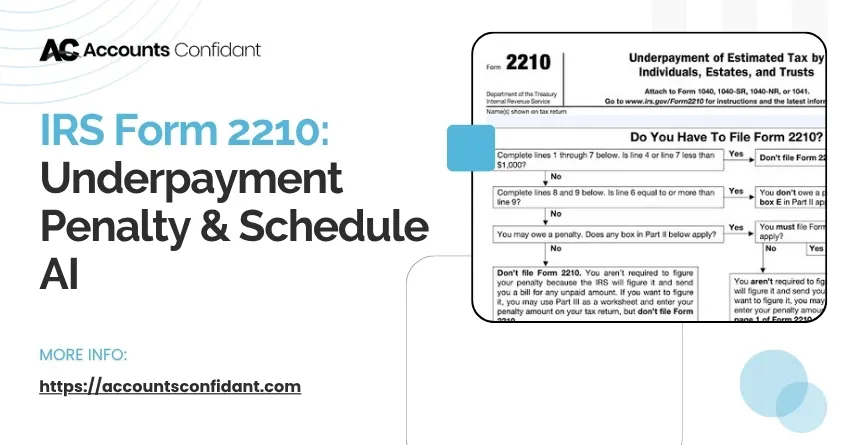
IRS Form 2210 helps taxpayers determine whether they owe a penalty for not paying enough federal income tax during the year through withholding and estimated tax payments. It is especially relevant to self-employed people, freelancers, investors, business owners, retirees, and others who do not have enough tax withheld from their income.
The form is more than a penalty calculator. It can also help you apply the prior-year tax safe harbor, use the annualized income installment method, and request a waiver when a qualifying situation caused the underpayment.
For 2026 tax planning, the IRS says the general required annual payment is based on the smaller of 90% of expected 2026 tax or 100% of 2025 tax, with a 110% prior-year threshold for certain higher-income taxpayers.
Important tax-year distinction: The IRS currently lists the final 2025 Form 2210 and 2025 instructions. For people searching for “Form 2210 instructions 2026,” 2026 estimated-tax rules can be found in IRS Publication 505, but the final 2026 Form 2210 should be used when it is released.
Official resources: IRS Form 2210 | Form 2210 Instructions | 2026 Publication 505
What Is IRS Form 2210?
IRS Form 2210, Underpayment of Estimated Tax by Individuals, Estates, and Trusts, is used to determine whether an estimated tax penalty applies and, in certain cases, to calculate that penalty.
The form is commonly relevant when your income comes from sources such as:
- Self-employment
- Freelance work
- Business income
- Investment income
- Capital gains
- Rental income
- Retirement income
- Other income without enough federal withholding
Form 2210 can also be useful when your income is uneven during the year. Schedule AI allows qualifying taxpayers to calculate required installments based on when income was actually earned instead of treating income as if it arrived evenly throughout the year.
Do You Need to File Form 2210?
Not everyone who owes an estimated tax penalty needs to file Form 2210. In many cases, the IRS calculates the penalty and sends a bill instead.
For the 2025 return, the IRS says you generally do not need to calculate the penalty yourself if none of the situations requiring Form 2210 applies. You can leave the estimated tax penalty line on your return blank and allow the IRS to calculate the penalty.
You may need to file Form 2210 when, for example:
- You are requesting a penalty waiver.
- You are using the annualized income installment method.
- You want to calculate the penalty yourself under a required filing situation.
- Another condition in the Form 2210 flowchart requires you to attach the form.
The Part II boxes on Form 2210 help determine whether you must calculate the penalty yourself.
Who Is Most Likely to Need Form 2210?
People without regular paycheck withholding are more likely to need to understand Form 2210 and estimated tax payments.
This includes:
- Freelancers
- Independent contractors
- Self-employed individuals
- Small business owners
- Real estate investors
- Stock and crypto investors
- Retirees with taxable income
- People receiving large bonuses
- Taxpayers with large capital gains
- Individuals with significant dividend or interest income
For example, an employee with all federal income tax withheld through payroll may have no estimated-payment problem, while a freelancer receiving 1099 income may need to make quarterly estimated payments.
When Do You Have to Pay Estimated Tax?
Estimated tax payments are generally made four times a year, but the payment schedule is based on income received during specific periods.
For most individual taxpayers, the regular federal estimated-tax due dates are generally:
| Payment | General due date |
| 1st payment | April 15 |
| 2nd payment | June 15 |
| 3rd payment | September 15 |
| 4th payment | January 15 of the following year |
If a due date falls on a weekend or legal holiday, the payment is generally due on the next business day.
The dates can be different for farmers, fishers, and taxpayers using special rules.
What Is the Underpayment of Estimated Tax Penalty?
The underpayment penalty is generally charged when you did not pay enough tax during the year through withholding and timely estimated tax payments.
The important point is that the IRS looks at when tax payments were made, not only how much you paid by the final tax-return deadline.
For example, suppose you owe $20,000 when you file your return but made sufficient payments throughout the year. You may not owe an estimated-tax penalty.
On the other hand, paying a large amount in April may not completely eliminate a penalty caused by earlier underpayments.
The IRS calculates the penalty separately for each required payment period.
How Is the Form 2210 Penalty Calculated?
The penalty is generally based on the amount you were required to pay for each installment period, the amount you actually paid, and how long an underpayment remained unpaid.
A simplified process is:
- Calculate your required annual payment.
- Determine the required amount for each payment period.
- Compare the required installment with your payments and withholding.
- Identify any underpayment.
- Determine how long the underpayment remained.
- Apply the IRS penalty rate for the relevant period.
- Add the amounts for the applicable periods.
The penalty rate is not a fixed percentage for every tax year. It can change during the year, so do not use an old Form 2210 penalty rate for a current return.
Why Timing Matters
Suppose your required installment was $5,000 for a payment period but you paid only $3,000.
Your initial underpayment is:
$5,000 − $3,000 = $2,000
If you later pay the remaining $2,000, the penalty may still apply for the period during which that $2,000 was unpaid.
This is why making a late catch-up payment does not always remove an earlier estimated-tax penalty.
What Is the Safe Harbor for Estimated Taxes?
The estimated-tax safe harbor can generally protect you from an underpayment penalty when your withholding and timely estimated payments meet the IRS’s required threshold.
For 2025, the general rule was that your payments needed to equal at least the smaller of:
- 90% of your current-year tax, or
- 100% of your prior-year tax, provided the prior-year return covered a full 12 months.
For 2026 estimated taxes, the IRS Publication 505 similarly states that the required annual payment is generally the smaller of:
- 90% of your expected 2026 tax, or
- 100% of your 2025 tax.
This is often called the 90% / 100% safe harbor.
What Is the 90% Rule for Estimated Taxes?
The 90% rule means you generally avoid the estimated-tax penalty when your qualifying payments during the year reach at least 90% of your current-year tax, subject to the other rules.
For example:
- Current-year tax: $30,000
- 90% of current-year tax: $27,000
If your withholding and timely estimated payments meet the applicable $27,000 threshold, the current-year safe harbor may protect you from the underpayment penalty.
This does not mean you can pay only 90% of your tax and owe nothing when you file. You still must pay your remaining balance by the tax-return deadline.
Safe harbor protects against the estimated-tax penalty; it does not eliminate the remaining income tax you owe.
What Is the 100% / 110% Prior-Year Safe Harbor?
The prior-year safe harbor generally allows you to avoid the estimated-tax penalty by paying at least 100% of the previous year’s tax, but certain higher-income taxpayers must use 110%.
For 2025, the IRS instructions use:
- 100% of prior-year tax for most taxpayers.
- 110% of prior-year tax when the applicable prior-year AGI is above $150,000, or $75,000 for married taxpayers filing separately.
For 2026 estimated taxes, the IRS uses the same basic higher-income threshold structure based on 2025 AGI.
Example
Suppose your 2025 tax was $40,000.
If the 100% prior-year safe harbor applies:
$40,000 × 100% = $40,000
You would generally need $40,000 in qualifying withholding and estimated payments during 2026 to meet that safe-harbor amount.
If the 110% rule applies:
$40,000 × 110% = $44,000
The prior-year safe harbor is useful because you do not need to know your exact current-year tax liability to use that test.
When Does the $1,000 Exception Apply?
You generally do not owe an estimated-tax penalty if the tax due after withholding is less than $1,000, after applying the IRS’s required calculation.
For the 2025 Form 2210 instructions, the IRS says this exception applies when:
Total tax shown on the return − tax paid through withholding < $1,000.
This is another reason you should not assume that owing a balance when you file automatically means you owe an estimated-tax penalty.
How Does Form 2210 Schedule AI Work?
Schedule AI, Annualized Income Installment Method, lets qualifying taxpayers calculate required estimated payments based on income earned during each period instead of assuming income arrived evenly throughout the year.
This can be particularly useful when your income changes significantly during the year.
Examples include:
- A freelancer who has a slow first quarter and a strong fourth quarter.
- An investor who realizes a large capital gain late in the year.
- A seasonal business owner.
- Someone who receives a large bonus near year-end.
- A person who sells an investment late in the year.
The method can reduce an earlier installment when the income that creates the tax was not received until later in the year.
What Are the Schedule AI Periods?
Schedule AI uses cumulative income periods rather than four equal one-quarter income calculations. The 2025 Form 2210 instructions use these periods:
| Schedule AI column | Income period |
| (a) | January 1–March 31 |
| (b) | January 1–May 31 |
| (c) | January 1–August 31 |
| (d) | January 1–December 31 |
Each period includes the previous period’s income.
For example, the May 31 column does not look only at April and May. It includes income from January 1 through May 31.
When Should You Use the Annualized Income Installment Method?
Schedule AI is most useful when your income is uneven and the regular quarterly method makes your estimated payments look higher than the tax actually required for earlier periods.
Consider an investor who has:
- Little taxable income during January–March.
- Moderate income through May.
- A large stock gain in November.
Using the regular method may treat the year’s required installments more evenly.
The annualized method can instead reflect the fact that the large gain happened later.
The IRS specifically notes that taxpayers with income that varies during the year may be able to lower or eliminate one or more required installments by using Schedule AI.
Can You Avoid the Underpayment Penalty If Income Was Uneven?
Potentially, yes. Schedule AI may reduce or eliminate an underpayment penalty when your income was uneven during the year and the annualized method correctly reflects when the income was received.
This is especially relevant for:
- Seasonal businesses
- Freelancers
- Investors
- Commission-based workers
- Business owners
- Taxpayers with late-year capital gains
There is an important rule: if you use Schedule AI for one payment period, you must use it for all payment periods.
Form 2210 Annualized Income Installment Method Example
A late-year income spike can make the annualized method useful because it aligns estimated payments more closely with when income was earned.
Suppose Sarah is a freelance designer.
Her income is approximately:
| Period | Income |
| January–March | $10,000 |
| January–May | $22,000 |
| January–August | $35,000 |
| Full year | $95,000 |
Most of Sarah’s income arrives during the last four months.
Under a simple quarterly approach, she might appear to have needed similar payments throughout the year.
Schedule AI instead looks at her cumulative income for each period and annualizes it under the IRS method.
If the calculations show that her tax liability was lower during the earlier periods, her required installments may also be lower for those periods.
This does not automatically remove the penalty. Sarah must complete Schedule AI and the related Form 2210 calculations correctly.
Form 2210 Short Method vs. Regular Method
The short method is a simplified penalty calculation available only in specific situations, while the regular method is used when the taxpayer does not qualify for the short method.
The IRS’s current 2025 Form 2210 instructions describe the penalty calculation through Part III, including Section A for underpayment and Section B for calculating the penalty. The instructions also allow the annualized income installment method through Schedule AI.
Older Form 2210 versions explicitly labeled a separate Short Method and Regular Method, which is why these terms still appear frequently in searches and tax software discussions.
For a current return, use the terminology and instructions printed on the Form 2210 for that tax year rather than relying on an older form.
When Is the Simplified Calculation Relevant?
Historically, the short method has generally been available when:
- No estimated tax payments were made, or
- Equal estimated payments were made on the four due dates.
Taxpayers with late estimated payments or certain other circumstances have generally needed the regular method.
For a current-year filing, check the exact year’s Form 2210 instructions before choosing a method.
How to Fill Out Form 2210
Start by calculating your required annual payment, then determine whether you need to calculate the penalty yourself or can have the IRS calculate it.
Step 1: Gather your tax information
Have these documents available:
- Current-year Form 1040 or applicable return
- Prior-year tax return
- W-2 forms
- 1099 forms
- Estimated tax payment records
- Federal withholding records
- Investment income records
- Business income and expense records
- Records of large capital gains
- Retirement income records
Step 2: Calculate the required annual payment
Part I of Form 2210 is used to determine your required annual payment.
The calculation considers current-year tax, applicable credits, withholding, and prior-year tax under the applicable safe-harbor rules.
Step 3: Check whether an exception applies
You may not owe the penalty if, for example:
- You had no tax liability in the prior year and meet the IRS requirements.
- Your tax due after withholding is less than $1,000.
- A special farmer or fisher rule applies.
- Another IRS exception applies.
Step 4: Determine whether Form 2210 must be attached
Use the flowchart and Part II boxes to determine whether you need to file the form.
Step 5: Choose the appropriate calculation method
Depending on your situation, you may use:
- The regular penalty calculation.
- The annualized income installment method.
- Another permitted calculation method.
Step 6: Calculate the penalty
Part III calculates the underpayment and penalty using the applicable payment periods.
Step 7: Report the penalty
If you calculate the penalty yourself, enter the result on the appropriate estimated-tax penalty line of your federal return. The 2025 Form 2210 instructions refer to Form 2210, line 19 and the estimated-tax penalty line on the tax return.
Does the IRS Automatically Calculate the Form 2210 Penalty?
Yes, in many cases the IRS calculates the estimated-tax penalty for you instead of requiring you to file Form 2210.
If you do not fall into one of the situations requiring Form 2210 and want the IRS to calculate the penalty, you generally complete your tax return without calculating the penalty yourself.
The IRS can then send you a notice showing the penalty.
If you disagree with the IRS calculation, you can review the notice and the applicable Form 2210 rules.
Can You E-File Form 2210?
Yes, Form 2210 can generally be included with an electronically filed federal tax return when your tax software supports the required form and calculation.
Tax software may calculate Form 2210 automatically based on the information entered in your return.
However, the software still needs accurate information about:
- Estimated tax payments
- Payment dates
- Federal withholding
- Prior-year tax
- Current-year tax
- Annualized income
- Applicable exceptions
Incorrect payment dates can produce an incorrect penalty calculation.
How to Request a Form 2210 Penalty Waiver
The IRS may waive all or part of an underpayment penalty when specific qualifying circumstances apply.
For 2025, the IRS lists waiver situations that include:
- You retired after reaching age 62 and the underpayment was due to reasonable cause rather than willful neglect.
- You became disabled and the underpayment was due to reasonable cause.
- The underpayment resulted from a casualty, disaster, or other unusual circumstance and imposing the penalty would be inequitable.
How Do You Request the Waiver?
The general process is:
- Complete the applicable portion of Form 2210.
- Check the appropriate waiver box.
- Provide a written explanation.
- Explain why you could not meet the estimated-tax requirement.
- State the period involved.
- Include supporting documentation when appropriate.
For retirement or disability, the IRS instructions call for documentation supporting the retirement date and age or the date of disability. For casualty or unusual circumstances, supporting documents may also be required.
The IRS reviews the request and decides whether the waiver applies.
What If You Were Affected by a Federal Disaster?
Taxpayers in federally declared disaster areas may receive automatic estimated-tax penalty relief when the IRS postpones the applicable payment deadline.
The IRS says it generally identifies eligible taxpayers while processing their returns and applies the appropriate disaster relief automatically.
If your underpayment was caused by a federally declared disaster, check the current IRS disaster-relief guidance before filing Form 2210.
An exception can apply when you use the annualized income installment method because Form 2210 may still be needed to calculate a lower penalty.
Special Rules for Farmers and Fishers
Farmers and fishers can have different estimated-tax rules when at least two-thirds of their gross income comes from farming or fishing.
For 2025, the IRS instructions substitute 66⅔% for the normal 90% current-year test when the required farming or fishing income test is met.
There are also special payment rules.
If you meet the applicable requirements, you may not owe an estimated-tax penalty when you file the return and pay the full tax by the special March deadline.
If you do not meet the farmer/fisher exception, Form 2210-F may apply instead.
Form 2210 for Retirees
Retirees can face an estimated-tax penalty when pension, IRA, investment, or other taxable income does not have enough federal withholding.
Retirees should not assume that being retired means estimated taxes are unnecessary.
For example, a retiree may have:
- Pension income
- Social Security benefits
- IRA distributions
- Required minimum distributions
- Dividend income
- Capital gains
One useful planning option is tax withholding from certain retirement distributions.
Federal withholding can count toward estimated-tax requirements and may help avoid the need for separate quarterly payments.
Form 2210 for Freelancers and Self-Employed Workers
Freelancers and self-employed taxpayers should estimate both their income tax and self-employment tax when planning estimated payments.
A common mistake is to calculate estimated payments using income tax alone.
Self-employed taxpayers may also have:
- Self-employment tax
- Additional Medicare Tax
- Net Investment Income Tax
- Other taxes included in the Form 2210 calculation
Because business income can change from month to month, keeping a running tax estimate throughout the year is often more useful than waiting until the fourth quarter.
Form 2210 for Investors and Capital Gains
Investors may need to adjust estimated payments when a large capital gain occurs during the year.
For example, suppose an investor has little taxable income during the first half of the year but sells stock in November and realizes a $200,000 gain.
A regular quarterly approach may not reflect when the gain occurred.
The annualized income installment method may be relevant because it allows qualifying taxpayers to calculate installments based on income through each period.
Investors should also remember that federal withholding can be treated differently from estimated payments because withholding is generally treated as paid evenly throughout the year for estimated-tax purposes, subject to the applicable rules.
Form 2210 Case Study: Freelancer With Uneven Income
A freelancer with low income early in the year and high income later may benefit from Schedule AI.
Consider Mark, a freelance consultant.
His income looks like this:
- January–March: $8,000
- April–May: additional $7,000
- June–August: additional $10,000
- September–December: additional $60,000
His largest income arrives late in the year.
Under a basic quarterly approach, his required installments may appear more evenly distributed.
With Schedule AI, Mark can calculate his tax based on cumulative income through each required period. The annualized method can therefore better reflect the timing of his income.
The IRS specifically provides Schedule AI for situations where income varies during the year.
Form 2210 vs. Form 1040-ES
Form 1040-ES is primarily used to calculate and pay estimated tax during the year, while Form 2210 is used to determine whether an underpayment penalty applies after the tax year.
| Form | Main purpose |
| Form 1040-ES | Estimate and pay federal income tax during the year |
| Form 2210 | Calculate or report an estimated-tax underpayment penalty |
| Schedule AI | Annualize income for Form 2210’s penalty calculation |
This distinction is useful for freelancers and business owners.
You generally use 1040-ES during the year to make estimated payments and may use Form 2210 after year-end to determine whether the payments were sufficient and timely.
Form 2210 vs. Form 2210-F
Form 2210 generally applies to individuals, estates, and trusts, while Form 2210-F is designed specifically for farmers and fishers who meet the applicable income test.
If at least two-thirds of your gross income comes from farming or fishing, special rules may apply.
The IRS provides a separate Form 2210-F, Underpayment of Estimated Tax by Farmers and Fishers.
Do not automatically use Form 2210-F simply because you have some farm or fishing income. The IRS income test must be met.
Form 2210 PDF: Where to Get It
The safest place to get a Form 2210 PDF is the official IRS website.
The IRS currently lists the 2025 Form 2210 PDF, posted January 14, 2026, along with the 2025 instructions posted February 26, 2026.
You can access:
Official Form 2210 Instructions
For a 2026 tax return, check the IRS forms page for the final 2026 version before filing.
Form 2210 Instructions 2026
For 2026 tax planning, use the IRS’s current 2026 estimated-tax guidance and the final 2026 Form 2210 when released.
The IRS’s 2026 Publication 505 currently provides guidance on estimated taxes and the annualized income installment method. It states that the general 2026 required annual payment is the smaller of:
- 90% of 2026 tax, or
- 100% of 2025 tax.
For certain higher-income taxpayers, the prior-year test becomes 110%.
The IRS also states that if you use the annualized income installment method to determine your 2026 estimated payments, you must file Form 2210 with the 2026 tax return.
Because Form 2210 is tax-year specific, do not copy line numbers, penalty rates, or thresholds from an older Form 2210 into a 2026 return without checking the current IRS instructions.
Common Form 2210 Mistakes
Most Form 2210 errors come from using the wrong safe harbor, ignoring payment dates, or failing to account for uneven income.
Assuming you need to pay 25% every quarter
The regular method may divide the required annual payment into installments, but your actual situation can involve withholding, prior-year safe harbor rules, and annualized income.
Using only the 90% rule
The prior-year safe harbor may be easier to use when you know your previous year’s tax.
Forgetting the 110% rule
Higher-income taxpayers may need to use 110% rather than 100% of prior-year tax.
Treating a late payment as if it were timely
A payment made in April cannot always erase an underpayment from an earlier installment period.
Ignoring withholding
Federal withholding can count toward your estimated-tax requirement.
Ignoring uneven income
A taxpayer with a large late-year gain or seasonal income may want to examine Schedule AI.
Using an old penalty rate
Form 2210 penalty rates can change. Always use the rate and instructions for the applicable tax year.
Using Schedule AI for only one quarter
The IRS says that if you use Schedule AI for any payment due date, you must use it for all payment due dates.
Assuming the IRS automatically waived your penalty
A waiver generally requires a qualifying reason and, in some cases, an explanation and supporting documentation.
Final Takeaway
IRS Form 2210 helps determine whether you owe a penalty because your federal tax payments were too low or too late during the year.
For most taxpayers, the first question is not “How do I fill out Form 2210?” It is “Do I actually need to calculate or file Form 2210?”
The key points are:
- The IRS often calculates the penalty for you.
- The general safe-harbor tests use 90% of current-year tax or 100% of prior-year tax.
- Certain higher-income taxpayers use 110% of prior-year tax.
- The $1,000 exception can prevent the penalty in qualifying situations.
- Schedule AI can help when income is uneven during the year.
- A qualifying retirement, disability, disaster, casualty, or unusual circumstance may support a penalty waiver.
- Estimated-tax penalties are based partly on when payments were made, not simply the total paid by the tax-return deadline.
For 2026 planning, the IRS’s current Publication 505 provides the applicable estimated-tax guidance, while taxpayers should use the final 2026 Form 2210 and instructions once available.
Frequently Asked Questions
What is IRS Form 2210?
IRS Form 2210 is used to determine whether you owe a penalty for underpaying federal estimated tax and, in certain cases, to calculate that penalty.
Do I need to file Form 2210?
Not always; the IRS calculates many estimated-tax penalties automatically. You may need to file Form 2210 when a required filing condition applies, such as requesting a waiver or using Schedule AI.
When do I have to file Form 2210?
Generally, Form 2210 is filed with your federal tax return for the applicable tax year when the form is required. The IRS may calculate the penalty for you when Form 2210 is not required.
How is the underpayment penalty calculated on Form 2210?
The calculation considers the required installment, actual payments and withholding, the amount underpaid, and how long the underpayment remained unpaid.
What is the safe harbor for estimated taxes?
The general safe harbor is the smaller of 90% of current-year tax or 100% of prior-year tax, with a 110% prior-year rule for certain higher-income taxpayers.
What is the 90% rule for estimated taxes?
It generally means that qualifying payments during the year equal at least 90% of your current-year tax, subject to the applicable rules.
What is the 100% / 110% prior-year safe harbor?
Most taxpayers can generally use 100% of the prior year’s tax. Certain higher-income taxpayers must use 110%.
How does Schedule AI on Form 2210 work?
Schedule AI annualizes your income, deductions, and other tax items through specific periods so required installments can reflect when income was actually earned.
When should I use the annualized income installment method?
It can be useful when your income is uneven, such as with seasonal business income, large late-year capital gains, or other income that arrives at different times.
Can I avoid the underpayment penalty if my income was uneven?
Potentially, schedule AI may reduce or eliminate an underpayment for qualifying taxpayers when income varies during the year.
How do I request a waiver of the underpayment penalty?
Use Form 2210 when required, select the appropriate waiver option, and provide an explanation and supporting documentation when applicable. The IRS decides whether the waiver applies.
What is the difference between the regular method and the short method on Form 2210?
The short method is a simplified calculation available only in specific situations. The regular method is used when the taxpayer does not qualify for the simplified calculation. Current forms and instructions should be followed because the form’s layout and terminology can change by tax year.
Does the IRS automatically calculate the underpayment penalty for me?
Often, yes. If you are not required to calculate it yourself, the IRS can calculate the penalty and send you a bill.
Can I e-file Form 2210?
Yes, form 2210 can generally be included with an electronically filed tax return when supported by the tax software and applicable filing method.
What are common mistakes on Form 2210?
Common mistakes include using the wrong safe harbor, ignoring the 110% rule, entering incorrect payment dates, overlooking withholding, and failing to consider Schedule AI when income was uneven.