A partnership generally does not file an income tax return like a C corporation. Instead, it files IRS Form 1065, U.S. Return of Partnership Income, to report the partnership’s income, gains, losses, deductions, credits, and other required information.
The partnership generally does not pay federal income tax on its ordinary partnership income. Instead, the income, deductions, gains, losses, and credits pass through to the partners, who report their respective shares on their own tax returns. Schedule K-1 (Form 1065) is the document that tells each partner what to report.
This guide explains Form 1065 instructions, who must file, the Form 1065 due date 2026, how to complete the return, how Schedule K and Schedule K-1 work, the Form 1065 late filing penalty, e-filing rules, common errors, and important tax-law changes.
2026 filing note: As of September 24, 2026, the IRS’s latest final Form 1065 and instructions are for tax year 2025, published in January 2026. The IRS has also posted a 2026 draft Form 1065, but taxpayers should not file the draft. The final 2026 form and instructions are expected to govern tax year 2026 returns generally filed in 2027.
What Is IRS Form 1065?
IRS Form 1065 is an informational federal tax return used by partnerships to report business activity and pass each partner’s share of tax items through to the partners. The partnership uses the return to report the partnership’s overall results; the partners use their Schedule K-1 information on their own returns.
For example, assume a two-member partnership earns $300,000 of ordinary business income for the year.
The partnership reports the $300,000 on Form 1065 and then allocates the appropriate amounts between the partners according to the partnership agreement and applicable tax rules.
The partnership does not simply file Form 1065 and stop there. It generally prepares a separate Schedule K-1 for each partner.
Why is Form 1065 called an informational return?
Form 1065 is called an informational return because its primary purpose is to tell the IRS how the partnership’s income and other tax items are determined and how those items are allocated among partners.
That does not mean the partnership has no tax responsibilities. A partnership can have other federal tax obligations, including certain withholding, excise, reporting, or partnership-level tax obligations depending on its circumstances.
The important distinction is that ordinary partnership income generally passes through to the partners instead of being taxed at the partnership level like C corporation income.
Who Must File Form 1065?
Most domestic partnerships must file Form 1065 unless they meet the narrow exception for having neither income nor expenditures treated as deductions or credits for federal tax purposes. Multi-member LLCs classified as partnerships generally follow the same rule.
Do multi-member LLCs have to file Form 1065?
A multi-member LLC generally files Form 1065 when it is classified as a partnership for federal income tax purposes. An LLC’s legal structure does not by itself determine which federal tax return it files.
An LLC can be classified federally in different ways depending on its ownership and elections.
For example:
- A multi-member LLC generally defaults to partnership treatment.
- An LLC that elects corporate treatment may file a corporate return instead.
- A single-member LLC generally has different federal tax reporting rules unless it elects another classification.
The first step is therefore to confirm the LLC’s federal tax classification before preparing Form 1065.
Who else may need to file Form 1065?
Certain foreign partnerships, religious or apostolic organizations, and other entities specifically treated as partnerships can have Form 1065 filing requirements.
A foreign partnership generally must file when it has income effectively connected with a U.S. trade or business or certain U.S.-source income, even when its main business is outside the United States or all its partners are foreign.
However, the IRS provides specific exceptions for certain foreign partnerships. For example, one exception can apply when there is no effectively connected income, U.S.-source income is $20,000 or less, less than 1% of relevant partnership items are allocable in the aggregate to direct U.S. partners, and the partnership is not a withholding foreign partnership. Other requirements apply to a different exception for foreign partnerships with no U.S. partners.
Foreign partnerships should not rely on a simple “foreign = no filing” rule.
Does an Inactive Partnership Have to File Form 1065?
An inactive partnership does not automatically avoid Form 1065 filing; the key question is whether it had any income or expenditures treated as deductions or credits for federal tax purposes.
This is often called the “zero-zero rule.” It is an informal description, not the name of an IRS program.
The IRS exception applies when the partnership has neither income nor expenditures treated as deductions or credits for federal income tax purposes.
For example, imagine an LLC that:
- Has no sales
- Has no customers
- Has no payroll
- Has no interest income
- Has no deductible expenses
The filing requirement may be different from an “inactive” LLC that still had a deductible bank fee, professional fee, or other business expense.
The safest approach is to review the partnership’s actual transactions rather than assuming that “no revenue” means “no Form 1065.”
A qualified opportunity fund has an additional special rule: it must file Form 1065 and attach Form 8996 even if it had no income or expenses to report.
When Is Form 1065 Due in 2026?
For a calendar-year partnership’s 2025 tax year, Form 1065 was generally due March 16, 2026, because March 15, 2026 fell on a Sunday. A timely six-month extension moved the filing deadline to September 15, 2026.
The normal rule is the 15th day of the third month after the partnership’s tax year ends.
For a calendar-year partnership:
Tax year ends: December 31, 2025
Normal date: March 15, 2026
Actual 2026 deadline: March 16, 2026
The IRS specifically confirmed March 16, 2026 as the timely filing date for calendar-year 2025 partnerships.
What is the extended Form 1065 deadline?
A partnership can generally request an automatic six-month extension by filing Form 7004 by the regular Form 1065 due date.
For a calendar-year partnership whose original 2025 return was due March 16, 2026, the extended filing deadline is generally September 15, 2026.
The extension gives additional time to file the return. It does not turn an otherwise late return into a timely return if Form 7004 itself was filed after the original deadline.
What about a partnership with a fiscal year?
Fiscal-year partnerships use the 15th day of the third month after the end of their tax year rather than automatically using March 15.
For example, a partnership whose tax year ends June 30 generally has a September 15 filing deadline.
This is why the tax year shown on Form 1065 matters when determining the correct due date.
Form 1065 Instructions 2026: Which Version Should You Use?
As of September 24, 2026, the IRS lists the final 2025 Form 1065 and 2025 instructions as the current published versions, while the 2026 Form 1065 available from the IRS is a draft and is marked not for filing.
This distinction matters because people searching for “Form 1065 instructions 2026” may actually be asking about two different filing years.
Form 1065 filed in 2026
A calendar-year partnership generally filed its 2025 Form 1065 in 2026.
The IRS released the final 2025 Form 1065 instructions in January 2026.
Form 1065 for tax year 2026
A calendar-year partnership’s 2026 Form 1065 generally will be filed in 2027.
The IRS has published a 2026 draft Form 1065, but that draft is labeled “DRAFT—NOT FOR FILING.”
Therefore, do not download an unofficial “2026 Form 1065 PDF” from a random website and assume it is the final filing form.
The official IRS forms page should be checked for the final revision.
How to Fill Out Form 1065
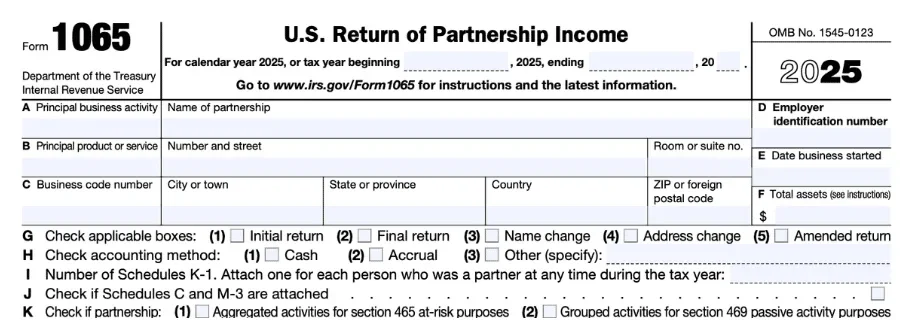
The best way to complete Form 1065 is to prepare the partnership’s accounting records first and then use those records to complete the return and its supporting schedules. The return should be built from the partnership’s actual books, partner records, tax adjustments, and supporting documents.
Step 1: Enter the partnership’s basic information
Start Form 1065 by confirming the partnership’s legal name, address, EIN, business activity, accounting method, tax year, and other identifying information.
The form can also require information such as the date the business started, total assets, number of Schedule K-1s, and whether the return is initial, final, amended, or reflects an address or name change.
Make sure the EIN on the return agrees with the partnership’s IRS records.
Step 2: Report ordinary business income
Report the partnership’s trade or business income on the appropriate lines of Form 1065, starting with gross receipts or sales and other applicable operating income.
The IRS instructions caution that rental activity and portfolio income generally should not simply be combined with ordinary trade or business income on page 1. Those amounts are generally separately reported through Schedule K and K-1, with rental real estate activity also reported on Form 8825 when applicable.
Common income categories can include:
- Gross receipts or sales
- Cost of goods sold
- Interest income
- Dividends
- Royalties
- Rental income
- Capital gains or losses
- Section 1231 gains
- Other income
The exact reporting location depends on the type of income.
Step 3: Report deductible business expenses
Form 1065 also reports the partnership’s allowable business deductions, including expenses such as salaries, guaranteed payments, rent, taxes, interest, depreciation, and other qualifying costs.
The partnership should maintain support for significant deductions.
For example, if a partnership reports $80,000 in advertising expenses, its accounting records should provide enough detail to support that amount.
A year-end bookkeeping process helps prevent a common problem: trying to rebuild the entire partnership’s financial activity while preparing the tax return.
Accounts Confidant’s bookkeeping help for tax preparation can be relevant when financial records need to be organized before tax filing.
Step 4: Separate items that must pass through to partners
Certain partnership items must be reported separately because the partners may apply different tax rules to them on their own returns.
Examples include:
- Capital gains and losses
- Charitable contributions
- Section 179 deductions
- Tax-exempt income
- Investment interest
- Foreign items
- Self-employment information
- Qualified business income information
- Certain credits
The partnership does not simply divide its final net profit into equal pieces and place the same number on every K-1.
The type of income or deduction matters.
Step 5: Prepare Schedule K and Schedule K-1
Schedule K summarizes the partnership’s total separately stated items, while Schedule K-1 reports each partner’s individual share.
This is one of the most important parts of Form 1065.
How Does Form 1065 Schedule K-1 Work?
Schedule K-1 tells each partner what share of partnership income, deductions, credits, and other tax information belongs to that partner. The partnership prepares a separate K-1 for every person who was a partner during the tax year.
For example, suppose Partnership ABC has two partners:
Partner A: 60%
Partner B: 40%
The partnership has $200,000 of ordinary business income and no special allocations.
The simplified allocation would be:
Partner A: $120,000
Partner B: $80,000
The actual K-1 can contain far more than ordinary income. It may include rental income, interest, dividends, capital gains, Section 179 deductions, credits, self-employment information, QBI information, distributions, and other items.
Does a partner pay tax even when no cash was distributed?
Yes, a partner can generally owe tax on their share of partnership income even when the partnership did not distribute that cash to them.
This is commonly called phantom income in casual business discussions.
For example, a partnership may earn $100,000 and retain $100,000 to purchase equipment or maintain cash reserves. A partner can still receive a K-1 reporting their share of the partnership’s taxable income.
Cash distributions and taxable income are not the same thing.
What does the partner do with Schedule K-1?
The partner generally uses the K-1 information to prepare the partner’s own federal and state tax returns. Depending on the type of item, information can flow to Form 1040 and schedules such as Schedule E or Schedule SE, or to other forms used to calculate specific deductions or taxes.
The partner generally does not attach Schedule K-1 to the individual return unless specifically instructed to do so. The partner should keep it with their tax records.
What Are the Important Form 1065 Schedules?
The schedules provide the detail behind the partnership’s financial results, partner allocations, balance sheet, book-to-tax differences, and other required information. The schedules required depend on the partnership’s activities and circumstances.
Schedule B
Schedule B is the “Other Information” section that asks questions about ownership, foreign activity, elections, related entities, reporting obligations, and other partnership facts.
Some questions can determine whether additional forms or schedules are required.
For example, Schedule B asks about foreign financial accounts, foreign partners, certain ownership interests, Section 754 elections, foreign transactions, and other tax matters.
Do not treat Schedule B as a routine yes-or-no page. The answers should be based on the partnership’s actual activity.
Schedule B-1
Schedule B-1 provides information about certain partners that directly or indirectly own 50% or more of the partnership’s profit, loss, or capital.
This is particularly important when a partnership has corporate, partnership, trust, estate, or other entity partners.
Schedule D
Schedule D reports certain capital gains and losses and related transactions that feed into the partnership’s separately stated capital-gain reporting.
A partnership selling investments, business property, or other assets may need Schedule D and supporting forms such as Form 8949 or Form 4797 depending on the transaction.
Schedule K
Schedule K summarizes the partnership-wide amounts that will be allocated among the partners on Schedule K-1.
Schedule K can include:
- Ordinary business income
- Rental real estate income
- Other rental income
- Guaranteed payments
- Interest
- Dividends
- Capital gains
- Section 1231 gains
- Other income
- Section 179 deductions
- Charitable contributions
- Other deductions
- Self-employment earnings
- Credits
- Foreign items
- Tax-exempt income
- Nondeductible expenses
- Distributions
- Other information
Schedule K-2 and Schedule K-3
Schedules K-2 and K-3 provide additional information about international tax items and can be required when a partnership has relevant international activity. They are extensions of the information reported on Schedule K and K-1.
The filing requirements are detailed and include specific exceptions.
A partnership should not assume that having only U.S. partners automatically means K-2 and K-3 can be ignored.
The 2025 instructions added an explicit Schedule K line 16b checkbox for certain partnerships claiming an exception from filing Schedule K-2.
Schedule L
Schedule L is the partnership’s balance sheet per its books and records. It generally reports assets, liabilities, and partners’ capital at the beginning and end of the year.
The balance sheet should agree with the partnership’s underlying records.
For example:
Assets = Liabilities + Partners’ capital
A difference between Schedule L and the accounting records should be investigated before filing.
Schedule M-1
Schedule M-1 reconciles income or loss reported on the partnership’s books with the income or loss reported on the tax return.
The difference can arise because financial accounting and tax accounting do not always treat items the same way.
For example, an expense may appear in the partnership’s financial statements but receive different tax treatment.
Schedule M-1 helps explain that difference.
Schedule M-2
Schedule M-2 shows changes in the partnership’s tax-basis capital accounts during the year.
It helps connect beginning capital, current-year income or loss, contributions, distributions, and other changes.
Smaller partnerships that meet the requirements in Schedule B, question 4 may not have to complete Schedules L, M-1, and M-2, although the return still has to be prepared correctly and the schedules can be required when the exception does not apply.
Schedule M-3
Schedule M-3 provides a more detailed book-to-tax reconciliation and is required for partnerships that meet specific asset, receipt, or ownership tests.
Under the 2025 instructions, Schedule M-3 is generally required instead of Schedule M-1 when, among other circumstances, the partnership has $10 million or more in total assets, $10 million or more in adjusted total assets, $35 million or more in total receipts, or certain reportable entity partner ownership exists.
A partnership should check the tax year’s actual M-3 rules rather than relying on an old asset threshold from a prior Form 1065.
What Are Guaranteed Payments on Form 1065?
Guaranteed payments are payments or credits to a partner that are determined without regard to partnership income and can relate to services or the use of capital.
For example, a partnership agreement may provide that one partner receives $60,000 for services regardless of whether the partnership earns a profit.
That payment can be treated differently from a partner’s distributive share of partnership profit.
On Schedule K-1, guaranteed payments are reported in:
- Box 4a: services
- Box 4b: use of capital
- Box 4c: total guaranteed payments
Do not simply treat every payment to a partner as a distribution.
How Does Self-Employment Tax Affect Form 1065?
Some partnership income and guaranteed payments can be included in a partner’s self-employment earnings, but the treatment depends on the partner’s status and the type of income.
For example, the IRS instructions contain specific rules for general partners and limited partners. A limited partner’s distributive share generally isn’t included in self-employment earnings, while guaranteed payments for services may be treated differently.
This is one reason why simply looking at the total K-1 amount is not enough.
Partners should review the specific boxes and codes on their K-1 rather than assuming that all partnership income has the same tax treatment.
What Are Partner Basis and Capital Accounts?
Partner basis determines whether a partner can generally use partnership losses and affects the tax treatment of distributions and the sale of a partnership interest. Capital accounts and outside basis are related but are not always the same number.
Inside basis vs. outside basis
Inside basis generally refers to the partnership’s tax basis in its assets, while outside basis generally refers to the partner’s adjusted tax basis in the partnership interest.
A partner’s outside basis can include the partner’s share of partnership liabilities, which is one reason it can differ from the partner’s tax-basis capital account reported by the partnership.
Section 754 and Section 743(b)
A Section 754 election can cause basis adjustments under Sections 743(b) and 734(b) when qualifying transfers or distributions occur.
For example, when a partner buys an existing partnership interest, a Section 743(b) adjustment may affect the buyer’s share of the partnership’s asset basis.
These rules become important when:
- A partner buys another partner’s interest
- A partner dies and the interest transfers
- Significant property is distributed
- A partnership has a Section 754 election in effect
The partnership must report applicable basis adjustments and provide supporting information when required.
Form 1065 vs. Form 1120-S
Form 1065 is generally filed by partnerships and LLCs taxed as partnerships, while Form 1120-S is generally filed by S corporations; both are pass-through structures but their owner reporting rules differ.
| Feature | Form 1065 | Form 1120-S |
| Common entity | Partnership or multi-member LLC taxed as partnership | S corporation |
| Owners called | Partners | Shareholders |
| Pass-through reporting | Yes | Yes |
| K-1 issued | Schedule K-1 (Form 1065) | Schedule K-1 (Form 1120-S) |
| Guaranteed payments | Can apply | No partnership-style guaranteed-payment system |
| Partnership liabilities | Reported on partnership K-1 | Treated under different basis rules |
| Self-employment treatment | Depends on partner and item | Generally wages handled through payroll for working shareholders |
| Filing deadline for calendar-year entity | March 15, subject to weekend/holiday rules | March 15, subject to weekend/holiday rules |
The two forms should not be selected based only on which one appears easier.
The entity’s legal structure, federal tax election, ownership, and actual tax classification determine the appropriate return.
For more detail on the corporate side, see Accounts Confidant’s S Corp vs. C Corp tax guide.
Form 1065 vs. Schedule C
Form 1065 is the partnership’s entity-level information return, while Schedule C generally reports business income and expenses directly on an individual’s Form 1040.
A sole proprietor generally uses Schedule C.
A partnership generally uses Form 1065.
A common mistake is to see an LLC’s business income and assume that every LLC should use Schedule C. That is not correct because an LLC can have different federal tax classifications.
For a qualifying joint venture owned by spouses, special rules can allow each spouse to report their respective business share on separate Schedule C or Schedule F returns rather than treating the venture as a partnership for federal income tax purposes.
What Is the Form 1065 Late Filing Penalty?
For partnership returns with a due date after December 31, 2025, the Form 1065 failure-to-file penalty is $255 per partner per month, or part of a month, generally for up to 12 months.
This penalty is calculated per partner, which can make a late return expensive even when the partnership itself owes no regular federal income tax.
Form 1065 penalty example
Suppose an LLC has two partners and its return is three months late.
The simplified late-filing penalty is:
$255 × 2 partners × 3 months = $1,530
A month or partial month generally counts under the penalty rules.
The penalty can generally continue for up to 12 months.
Reasonable-cause relief may be available in appropriate cases, and the IRS has special rules for certain small partnerships.
What is the Schedule K-1 penalty?
A separate penalty of $340 may apply for each Schedule K-1 that is not furnished on time, is incomplete, or contains incorrect required information.
This means a partnership can have two different compliance problems:
Late Form 1065
and
Late or incorrect Schedule K-1s
Both should be included in the filing calendar.
Can You E-File Form 1065?
Yes, Form 1065 can be electronically filed, and certain partnerships are required to e-file.
Beginning in 2024, partnerships generally have to electronically file Form 1065 and related forms and schedules when they file 10 or more returns of any type during the tax year.
Partnerships with more than 100 partners are also subject to mandatory electronic filing rules for Form 1065, Schedule K-1, and related forms and schedules.
The IRS uses the Modernized e-File (MeF) system for electronic partnership returns.
A partnership preparing its own return may need to work through an authorized process or use an IRS-authorized e-file provider, depending on its situation.
What if the partnership cannot e-file?
The IRS may grant a waiver from mandatory electronic filing when the partnership demonstrates that filing electronically would create a hardship, subject to the applicable waiver process.
There is also a religious exemption in certain circumstances.
Do not simply print a return and mail it when the partnership is subject to mandatory e-file rules without checking whether an exception or waiver applies.
How Does the One Big Beautiful Bill Act Affect Form 1065?
The One Big Beautiful Bill Act (OBBB/OBBBA), enacted July 4, 2025, changed several business tax rules that can affect partnership deductions and the information passed to partners through Form 1065 and Schedule K-1.
The exact effect depends on the partnership’s activity and tax year.
Domestic research and experimental expenses
Section 174A generally allows qualifying domestic research and experimental expenses paid or incurred in tax years beginning after 2024 to be deducted currently, with an alternative capitalization election.
This can matter for a partnership that performs qualifying domestic research.
Certain small businesses may also have transition options under the applicable rules.
100% additional first-year depreciation
OBBBA made 100% additional first-year depreciation permanent for qualifying property acquired after January 19, 2025, subject to the applicable rules.
A partnership purchasing qualifying equipment or other property should review the depreciation rules for the relevant tax year rather than automatically copying the prior year’s treatment.
Schedule K-2 and K-3 exception reporting
The 2025 Form 1065 added a Schedule K question 16b checkbox for certain partnerships that qualify for an exception from filing Schedule K-2.
This matters for partnerships trying to determine whether international reporting schedules are required.
Foreign-partner reporting
The 2025 instructions updated Schedule B, question 19 to include certain payments received that are allocable to foreign partners.
Partnerships with foreign partners should separately review withholding and reporting requirements.
For example, a partnership with effectively connected U.S. business income and foreign partners may have withholding obligations and may need Forms 8804, 8805, and 8813.
IRA partners receiving UBTI
For tax years after 2025, partnerships with an IRA partner receiving an allocation of unrelated business taxable income generally must include the IRA partner’s EIN on Schedule K-1 under the applicable code AR reporting rules.
This is particularly important for partnerships whose ownership includes retirement accounts.
Sound recording expenses
OBBBA expanded Section 181 to include certain qualified sound recording production costs, but the 2025 Form 1065 instructions describe the specific election for qualifying productions commencing before tax year 2026.
Therefore, this provision should not be described as a blanket new deduction for every 2026 partnership return. The production date and tax year matter.
What Are Common Form 1065 Mistakes?
The most common Form 1065 errors involve filing the wrong form, missing the filing deadline, incorrect partner allocations, K-1 errors, incomplete schedules, and bookkeeping records that do not agree with the tax return. Recent partnership guidance also emphasizes the need to reconcile K-1s to the partnership return and keep partner information current.
Filing Form 1065 late
A partnership may assume that no tax is owed at the entity level, so there is no urgency.
That is a mistake.
The partnership return itself can still face a per-partner filing penalty.
Assuming an inactive partnership never files
“No revenue” does not automatically mean “no Form 1065.”
Check whether the partnership had any income or deductible expenditures.
Dividing every item using the same percentage
Partners’ distributive shares generally follow the partnership agreement and applicable allocation rules.
Special allocations can apply, but they must satisfy the applicable tax rules.
Forgetting mid-year ownership changes
If a partner joins, leaves, contributes additional capital, or receives a distribution that changes the partner’s interest during the year, the allocation calculation may need special treatment.
Treating distributions as taxable income
A partnership distribution is not simply another line of ordinary business income.
Income allocation, distributions, and basis are separate concepts.
Ignoring guaranteed payments
Payments to partners for services or the use of capital may need to be reported as guaranteed payments rather than ordinary distributions.
Preparing K-1s after the partnership return deadline
The partnership generally has to furnish each partner’s Schedule K-1 by the date the partnership return is required to be filed, including applicable extensions.
Forgetting foreign reporting
Foreign partners, foreign accounts, international transactions, and foreign entities can create additional reporting requirements.
A domestic partnership with foreign partners may also have withholding responsibilities.
Using outdated thresholds and instructions
Old Form 1065 articles can contain thresholds, schedules, and due dates from prior years.
For example, the existing Accounts Confidant article contains 2019/2020-era guidance and is therefore not a reliable source for current filing rules.
Illustrative Case Study: Two-Member LLC With No Sales
An LLC with no sales can still have a Form 1065 filing obligation when it has deductible expenditures, so the owners should review the full year’s activity before deciding that no return is needed.
Suppose two owners form an LLC in January.
During the year, the LLC:
- Has no customers
- Generates no sales
- Has no employees
- Pays $600 in bank fees
- Pays $500 for accounting services
- Keeps $5,000 in its business bank account
The owners conclude that the LLC made “zero income.”
But the LLC did incur expenditures that may be treated as deductions for federal tax purposes.
Therefore, the partnership should not automatically assume that it qualifies for the no-income/no-deduction filing exception.
The preparer should review the transactions, the LLC’s federal classification, and the tax treatment of the expenses before deciding whether Form 1065 is required.
This is an illustrative example, not a reported Accounts Confidant client result.
Form 1065 Filing Checklist
A final review should cover the partnership’s books, partner information, schedules, K-1s, filing deadline, and required supporting forms before Form 1065 is submitted.
Partnership information
- Legal partnership name
- EIN
- Address
- Tax year
- Accounting method
- Business activity
- Date business started
- Initial/final/amended status
- Total assets, when required
Income and expense records
- Gross receipts
- Cost of goods sold
- Interest
- Dividends
- Royalties
- Rental income
- Capital gains and losses
- Section 1231 gains or losses
- Salaries and wages
- Guaranteed payments
- Rent
- Taxes
- Interest expense
- Depreciation
- Advertising
- Other deductible expenses
Partner records
- Partner names
- SSNs/EINs as applicable
- Ownership percentages
- Profit and loss percentages
- Capital contributions
- Distributions
- Partner loans
- Changes in ownership during the year
- Guaranteed payments
- Partner liabilities
- Special allocations
Tax schedules and forms
- Schedule B
- Schedule D
- Schedule K
- Schedule K-1
- Schedule K-2/K-3, when required
- Schedule L
- Schedule M-1 or M-3
- Schedule M-2
- Form 8825, when applicable
- Form 4562, when applicable
- Form 7004, if requesting an extension
- Forms 8804/8805/8813, when foreign-partner withholding applies
Final checks
Before filing, compare:
General ledger → trial balance → financial statements → partner allocations → Schedule K → individual K-1s → supporting schedules → final Form 1065
The total amounts allocated to partners should reconcile to the partnership-level amounts reported on Schedule K.
When Should a Partnership Get Professional Help With Form 1065?
Professional help becomes particularly useful when a partnership has multiple partners, changing ownership, special allocations, foreign partners, real estate activity, significant asset purchases, related-party transactions, large distributions, or complicated basis adjustments.
Partnership returns can be more complex than they initially appear because the return has two levels:
Partnership reporting
and
Partner-level reporting
An error on Form 1065 can flow into multiple K-1s and then into multiple partner tax returns.
Keeping the books clean throughout the year reduces the risk of discovering unresolved transactions at filing time.
Accounts Confidant provides bookkeeping and accounting support for businesses using third-party accounting software. Bookkeeping for tax preparation can help businesses organize financial records before their tax preparer works on the return.
Final Takeaway
IRS Form 1065 is the federal informational return generally used by partnerships to report their income, deductions, gains, losses, credits, and partner allocations.
The most important compliance points are straightforward:
A domestic partnership generally must file unless it meets the narrow zero-income/zero-deduction exception. Multi-member LLCs classified as partnerships generally follow the same rule. Certain foreign partnerships can also have filing requirements.
For 2026 filing, the calendar-year 2025 Form 1065 deadline was March 16, 2026, with a timely six-month extension generally moving the deadline to September 15, 2026.
Schedule K summarizes partnership-level information, while Schedule K-1 passes each partner’s share through to the partner. A partner can owe tax on allocated income even when cash was not distributed.
The Form 1065 late filing penalty is currently $255 per partner per month for returns due after December 31, 2025, generally for up to 12 months, and separate K-1 penalties can apply.
Finally, do not confuse a 2026 filing year with a 2026 tax year. As of September 24, 2026, the IRS lists the final 2025 Form 1065 and instructions as its current published version, while its 2026 Form 1065 is still marked as a draft for planning purposes.
IRS Form 1065 FAQ
Does every partnership get a Schedule K-1?
Generally, yes. A partnership generally prepares a separate Schedule K-1 for every person who was a partner during the tax year and furnishes it by the partnership return’s required filing date, including applicable extensions.
Does the partnership send Schedule K-1 to the IRS?
Yes, the partnership attaches the K-1 information to Form 1065 and provides a copy to each partner.
Can a partner change a K-1 number on their personal tax return?
A partner should not simply change a partnership item because it appears incorrect. The partner should generally contact the partnership for a corrected K-1 or follow the applicable IRS reporting procedure for inconsistent treatment.
Does a partnership tax return show each partner’s ownership percentage?
Yes, Form 1065 collects partner information, including profit, loss, and capital interests, and Schedule K-1 reports each partner’s allocated items. The exact allocation may differ from a simple ownership percentage when valid special allocations apply.
Is Form 1065 the same as a Schedule K-1?
No, Form 1065 is the partnership’s information return. Schedule K-1 is the partner-specific statement generated from that return.
What happens when a partner’s ownership changes during the year?
The partnership may need to allocate income, gains, losses, and deductions between the periods before and after the ownership change using the applicable partnership tax rules.
Does a partnership have to file Schedule M-1?
Not always. Certain smaller partnerships can have an exception that makes Schedules L, M-1, and M-2 optional, while larger or otherwise qualifying partnerships may need Schedule M-3 instead.