A C corporation generally has to file a federal income tax return every year, even when it has no taxable income. For most domestic corporations, that return is IRS Form 1120, U.S. Corporation Income Tax Return.
Form 1120 reports the corporation’s income, gains, deductions, credits, taxable income, and federal income tax liability. It also includes schedules that connect the tax return to the corporation’s accounting records and provide information about ownership, accounting methods, foreign activity, and other tax matters.
This guide explains Form 1120 instructions, filing requirements, the Form 1120 due date 2026, Schedule K, Schedule M-1, penalties, e-filing, common mistakes, and important 2026 tax-law changes.
2026 update: As of September 2026, the IRS has posted a draft 2026 Form 1120, but it is clearly marked “DRAFT—NOT FOR FILING.” The IRS’s latest final Form 1120 and final instructions are for tax year 2025. The IRS says the 2025 form may also be used for certain short tax years beginning and ending in 2026 when the 2026 form is not yet available.
What Is IRS Form 1120?
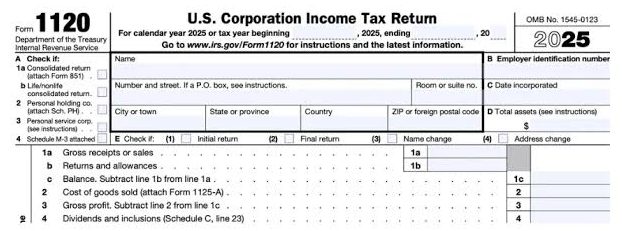
IRS Form 1120 is the federal income tax return used by domestic corporations that are taxed as regular corporations, commonly called C corporations. The corporation uses it to report business income and expenses and calculate its federal corporate income tax.
A corporation is a separate taxpayer from its shareholders. That means the corporation generally files its own federal income tax return and pays corporate income tax on its taxable income.
Form 1120 is different from an owner’s individual tax return. A shareholder may also have a separate tax reporting obligation when receiving items such as dividends or compensation.
For example, assume ABC Technology Inc. is organized as a corporation and has not elected S corporation treatment. Its business earns $800,000 in revenue and has $600,000 of allowable deductions.
The corporation does not simply report the $200,000 profit on an owner’s Form 1040. The corporation generally reports its own results on Form 1120.
What does Form 1120 report?
Form 1120 can report:
- Gross receipts or sales
- Cost of goods sold
- Interest and other income
- Salaries and wages
- Rent
- Taxes
- Depreciation
- Advertising
- Employee benefit expenses
- Other allowable deductions
- Net operating losses
- Certain credits
- Estimated tax payments
- Taxable income
- Federal corporate income tax
The exact schedules and supporting forms depend on the corporation’s activities.
Who Must File Form 1120?
Most domestic corporations must file an income tax return even when they have no taxable income. A domestic corporation generally files Form 1120 unless the tax law requires or permits it to file a different corporate return.
C corporations
A regular domestic C corporation generally files Form 1120.
This includes corporations that operate a traditional business, hold investments, own property, or conduct other taxable activities.
LLCs taxed as corporations
An LLC does not automatically file Form 1120 just because it is an LLC.
An LLC’s federal tax classification depends on its structure and elections. An LLC that has elected to be taxed as a corporation generally files the appropriate corporate return, including Form 1120 when it is taxed as a regular corporation.
This is why business owners should confirm their federal tax classification before preparing a return.
Inactive corporations
A domestic corporation generally still has a filing requirement even when it had no income.
The IRS instructions specifically state that domestic corporations must file an income tax return whether or not they have taxable income, subject to applicable exceptions.
For example, a corporation formed in January that never started operations should not assume that “no activity” automatically means “no Form 1120.”
Who generally files a different form?
Some organizations use specialized returns instead of Form 1120. Examples include S corporations filing Form 1120-S, partnerships filing Form 1065, and certain insurance companies, cooperatives, REITs, RICs, political organizations, and other specialized entities.
Before filing, confirm the entity’s federal tax classification and whether a special return applies.
For a broader comparison of corporate structures, see Accounts Confidant’s guide to S Corp vs. C Corp taxes.
What Is the Form 1120 Due Date in 2026?
For a calendar-year corporation, the 2025 Form 1120 was generally due April 15, 2026. For a calendar-year corporation filing its 2026 tax return, the general due date will be April 15, 2027.
The general rule is the 15th day of the fourth month after the end of the corporation’s tax year. A special rule applies to corporations with a fiscal year ending June 30. If the due date falls on a Saturday, Sunday, or legal holiday, the filing deadline moves to the next business day.
| Tax year | General Form 1120 due date |
| Calendar year 2025 | April 15, 2026 |
| Calendar year 2026 | April 15, 2027 |
| Fiscal year ending June 30, 2026 | September 15, 2026 |
| Fiscal year ending September 30, 2026 | January 15, 2027 |
The actual deadline depends on the corporation’s tax year, so do not automatically use April 15 for every corporation.
How do you extend Form 1120?
A corporation generally requests an automatic extension by filing Form 7004 by the original Form 1120 due date. The automatic extension for most C corporations is generally six months.
An extension gives the corporation additional time to file the return, not additional time to pay the tax.
Any expected tax should generally be paid by the original due date to reduce potential interest and late-payment charges.
Form 1120 Instructions 2026: What Should You Use?
The IRS has a 2026 draft Form 1120, but taxpayers should not file that draft. As of September 2026, the IRS’s current final Form 1120 instructions are for 2025.
This distinction matters when searching for a Form 1120 PDF or Form 1120 instructions 2026 online.
The IRS draft page specifically warns that draft forms are not for filing. Draft forms can change before final approval.
For a return that must be filed in 2026, the finalized 2025 Form 1120 and instructions generally provide the applicable filing framework. A qualifying short-year return beginning and ending in 2026 may also use the 2025 form if the 2026 form is not available when the return is required, with applicable 2026 tax-law changes taken into account.
How to Fill Out Form 1120
The easiest way to prepare Form 1120 is to complete the corporation’s books and supporting schedules first, then use those records to prepare the tax return. Form 1120 should be prepared from organized accounting records rather than estimating figures directly on the form.
Step 1: Enter the corporation’s basic information
Start with the identifying information, including:
- Corporation’s legal name
- Address
- Employer Identification Number (EIN)
- Date incorporated
- Total assets
- Tax year
- Initial or final return status, when applicable
- Name or address changes, when applicable
The corporation’s legal name should match its corporate records.
Step 2: Report income
Form 1120’s income section starts with gross receipts or sales and includes other applicable income items.
Depending on the corporation, income may include:
- Sales
- Service revenue
- Interest
- Rents
- Capital gains
- Dividends and inclusions
- Other taxable income
Businesses with inventory may also need Form 1125-A, Cost of Goods Sold. The amount from that form flows to Form 1120.
The key is to make sure the tax return agrees with the corporation’s accounting records after required tax adjustments are made.
Step 3: Report deductible expenses
The deductions section captures the corporation’s allowable business expenses.
Common categories include:
- Compensation of officers
- Salaries and wages
- Repairs and maintenance
- Bad debts
- Rent
- Taxes and licenses
- Interest
- Depreciation
- Advertising
- Pension and employee benefits
- Other deductions
A bookkeeping system should make it possible to trace major amounts on the return to supporting records.
Accounts Confidant’s bookkeeping services for small businesses can be useful when the accounting records need to be organized before tax preparation.
Step 4: Calculate taxable income
After income and deductions are reported, Form 1120 calculates taxable income before and after applicable net operating loss and special deductions.
For the 2025 Form 1120, taxable income ultimately appears on page 1, line 30.
Do not assume that the net profit shown on the company’s bookkeeping reports is automatically the same as taxable income.
Some expenses are treated differently for financial reporting and tax reporting, which is one reason Schedule M-1 or Schedule M-3 may be required.
Step 5: Calculate corporate tax and payments
Schedule J is used to calculate tax and certain credits and payments.
For regular corporate income tax, the 2025 Form 1120 instructions state that the corporation generally calculates income tax by multiplying taxable income by 21%.
The return then accounts for applicable credits, estimated tax payments, withholding, other payments, and certain additional taxes.
A corporation that expects its total tax, after applicable credits, to be $500 or more generally must make estimated tax installments during the year.
What Are the Important Form 1120 Schedules?
The schedules provide additional detail that supports the corporation’s income tax calculation and explains information that does not fit directly on page 1. The schedules required depend on the corporation’s size, ownership, transactions, and tax situation.
Schedule C
Schedule C deals with dividends, inclusions, and certain special deductions.
It is important not to confuse Schedule C on Form 1120 with Schedule C used by a sole proprietor on Form 1040.
Schedule J
Schedule J handles tax computation and payment information.
It can include the regular income tax calculation, corporate alternative minimum tax, credits, estimated tax payments, withholding, and other applicable amounts.
Schedule K
Schedule K is titled Other Information.
It asks questions about the corporation’s accounting method, business activity, ownership, foreign interests, NOL information, certain transactions, and other tax-related matters. The current 2026 draft retains Schedule K as an “Other Information” schedule.
Schedule L
Schedule L is the corporation’s balance sheet per books.
It reports assets, liabilities, and shareholders’ equity at the beginning and end of the tax year. The IRS instructions state that the balance sheet should agree with the corporation’s books and records.
Schedule M-1
Schedule M-1 reconciles book income or loss with income reported on the tax return.
It helps explain why accounting income does not always equal taxable income.
Schedule M-2
Schedule M-2 tracks changes in the corporation’s unappropriated retained earnings per its books.
It is related to the corporation’s equity records rather than being a second calculation of taxable income.
Schedule M-3
Schedule M-3 is a more detailed book-to-tax reconciliation for larger corporations.
A corporation with total assets of $10 million or more at the end of the tax year generally must file Schedule M-3 instead of Schedule M-1, subject to the detailed rules and exceptions in the instructions.
What Is Form 1120 Schedule K?
Schedule K is the “Other Information” section of Form 1120; it is not the same type of Schedule K used by a partnership or S corporation to allocate income to owners.
This is an important distinction because “Schedule K” means different things on different tax returns.
The Form 1120 Schedule K can ask about:
- Accounting method
- Business activity code
- Business activity and product or service
- Affiliated groups
- Ownership interests
- Foreign ownership
- Dividends exceeding earnings and profits
- NOL information
- Smaller-corporation filing exceptions
- Certain reporting requirements
- Digital assets
- Business interest expense issues
- Corporate alternative minimum tax
- Other corporate tax matters
The current 2026 draft Form 1120 shows these types of questions on Schedule K, including questions concerning ownership, NOLs, digital assets, business interest, CAMT, and corporate stock-repurchase excise tax reporting.
Why does Schedule K matter?
Schedule K can trigger additional forms or reporting requirements based on the answers.
For example, the 2026 draft asks questions related to foreign ownership, Schedule G, Form 5472, Form 8990, Form 4626, Form 7208, and other reporting requirements.
That is why checking “No” across the schedule without reviewing the underlying facts can create filing problems.
What Is Form 1120 Schedule M-1?
Schedule M-1 explains differences between the corporation’s book income and the income reported for federal tax purposes. It is essentially a bridge between financial accounting and tax reporting.
For example, assume a company has:
Book income: $250,000
Tax-exempt interest: $5,000
Nondeductible expenses: $8,000
Tax depreciation adjustment: $20,000
The final taxable income will not necessarily equal the $250,000 shown on the company’s books.
Schedule M-1 helps explain these differences.
Common book-to-tax adjustments may include:
- Nondeductible expenses
- Tax-exempt income
- Depreciation differences
- Certain meals and entertainment adjustments
- Accrued expenses treated differently for tax
- Other tax adjustments
The IRS instructions specifically identify nondeductible expenses and tax-exempt interest as items that may appear in the reconciliation.
When is Schedule M-1 not required?
Corporations with total receipts and total assets below $250,000 can generally avoid completing Schedules L, M-1, and M-2 when the applicable Schedule K question is answered “Yes.” Corporations with $10 million or more in total assets generally move to Schedule M-3 instead.
The exact requirements should be checked against the tax year’s instructions.
Form 1120 vs. Form 1120-S vs. Form 1065
Form 1120 is generally used by C corporations, Form 1120-S by S corporations, and Form 1065 by partnerships and LLCs taxed as partnerships. These returns have different tax reporting systems and should not be treated as interchangeable.
| Feature | Form 1120 | Form 1120-S | Form 1065 |
| Common entity | C corporation | S corporation | Partnership |
| Federal tax treatment | Corporate-level tax | Generally pass-through | Generally pass-through |
| Owner allocation | No Schedule K-1 for ordinary C-corp profits | Schedule K-1 | Schedule K-1 |
| Regular federal corporate rate | 21% | Generally income passes through | Generally income passes through |
| Main return | U.S. Corporation Income Tax Return | U.S. Income Tax Return for an S Corporation | U.S. Return of Partnership Income |
| Typical filing deadline | 4th month after year-end | 3rd month after year-end | 3rd month after year-end |
The form to file depends on the entity’s federal tax classification and elections, not simply on whether the business owner calls the company an “LLC” or “corporation.”
For an existing C corporation considering S corporation status, eligibility and the tax consequences of the election should be reviewed before filing Form 2553.
What Is the Corporate Tax Rate for 2026?
The regular federal corporate income tax rate for a C corporation is 21%. The 2025 Form 1120 instructions continue to direct corporations to calculate regular income tax at 21% of taxable income.
For example, if a corporation has $300,000 of taxable income and no other applicable tax adjustments or credits, the basic federal income tax calculation would be:
$300,000 × 21% = $63,000
That simplified example does not account for credits, additional taxes, NOL rules, special deductions, or other provisions that can affect the final amount.
State corporate income taxes are separate and may also apply.
How Does the One Big Beautiful Bill Act Affect Form 1120?
The One Big Beautiful Bill Act (OBBBA), enacted as Public Law 119-21 on July 4, 2025, changed several business tax rules that can affect amounts reported on Form 1120. The corporate 21% rate itself remains in place, but deductions, depreciation, research costs, and other calculations changed.
100% additional first-year depreciation
OBBBA made the 100% additional first-year depreciation deduction permanent for qualifying property acquired after January 19, 2025, subject to the applicable rules.
This can significantly affect depreciation deductions for corporations that purchase qualifying business property.
Higher Section 179 expensing limit
The law increased the Section 179 expense limit to $2.5 million for property placed in service in tax years beginning after December 31, 2024. The deduction begins to phase out when the total cost of qualifying property placed in service exceeds $4 million, with amounts adjusted for inflation after 2025.
Domestic research and experimental expenses
A new Section 174A generally allows corporations to deduct domestic research and experimental expenditures paid or incurred in tax years beginning after December 31, 2024.
A corporation can instead elect to capitalize qualifying domestic research costs and amortize them over at least 60 months under the applicable rules. Special transition provisions can apply to older amounts that were previously capitalized.
Business interest expense calculations
OBBBA also changed the Section 163(j) business interest limitation rules. For tax years beginning after December 31, 2024, depreciation, amortization, or depletion can again be added back when determining adjusted taxable income for the limitation. Additional changes apply for tax years beginning after December 31, 2025, including changes involving certain controlled-foreign-corporation income inclusions.
These rules can become complicated for corporations with substantial financing or international activity.
The important point is that a 2026 Form 1120 cannot simply copy last year’s deductions without reviewing the tax law applicable to the corporation’s tax year.
Can You E-File Form 1120?
Yes, Form 1120 can generally be e-filed through an approved IRS filing provider or tax professional. Corporations can generally electronically file Form 1120 along with related schedules, forms, and attachments.
There is also a mandatory e-file rule for many corporations.
For returns filed on or after January 1, 2024, a corporation generally must e-file Form 1120 when it files 10 or more returns of any type during the calendar year, subject to applicable waiver rules.
The 10-return calculation can include different types of returns, such as income, employment, excise, and information returns.
What Is the Form 1120 Late Filing Penalty?
A corporation that files Form 1120 late can generally face a penalty of 5% of unpaid tax for each month or part of a month the return is late, up to 25%. Reasonable-cause relief may be available in appropriate circumstances.
For returns required to be filed in 2026, the minimum failure-to-file penalty when a Form 1120 is more than 60 days late is generally the smaller of the tax due or $525.
Late payment is different from late filing
A corporation can face a separate penalty for paying tax late.
The general failure-to-pay penalty described in the Form 1120 instructions is 0.5% of unpaid tax for each month or part of a month, generally up to 25%. Interest may also apply.
This is why filing an extension does not mean the corporation can wait until the extended filing date to pay its tax without consequences.
What Are Common Form 1120 Mistakes?
Most Form 1120 problems come from incorrect entity information, missing schedules, unsupported deductions, mismatched accounting records, or missed filing and payment requirements. A final review should compare the return with the corporation’s books and prior-year return.
Using the wrong filing deadline
The Form 1120 due date depends on the corporation’s tax year.
Do not use the S corporation or partnership deadline for a C corporation. Form 1120 generally follows the fourth-month rule, while Forms 1120-S and 1065 generally use a different deadline.
Assuming no income means no return
A domestic corporation generally must file even when it has no taxable income.
Confusing book income with taxable income
The income shown on financial statements may differ from federal taxable income.
Review Schedule M-1 or M-3 and supporting tax adjustments before submitting the return.
Treating Schedule K like an S corporation Schedule K
Form 1120 Schedule K is an Other Information schedule. It is not the owner-income allocation schedule found on Form 1120-S.
Missing supporting forms
Depending on the corporation’s activities, the return may require additional forms such as Form 1125-A, Form 4562, Form 8990, Form 8993, Form 1118, Form 5472, Form 4626, or other schedules and statements.
Ignoring foreign ownership questions
A corporation with certain foreign ownership can have additional information-reporting obligations. The current Form 1120 Schedule K asks about significant foreign ownership and can point the corporation toward Form 5472 reporting.
Forgetting estimated tax payments
A corporation expecting at least $500 of tax after applicable credits generally must make estimated tax installments.
Filing a draft 2026 PDF
This is a current issue because the IRS has already published a 2026 draft Form 1120.
Do not file the draft. The IRS marks the draft as “DRAFT—NOT FOR FILING,” and the final form can contain changes.
Illustrative Case Study: Preparing Form 1120 for an Inactive Corporation
Consider a corporation formed in 2026 by two founders. The corporation obtained an EIN and opened a bank account but never began operating. It had no sales, no payroll, and no taxable income.
The owners assume that no tax return is necessary because there was no income.
That assumption can be wrong.
Because a domestic corporation generally has a federal income-tax filing requirement regardless of whether it has taxable income, the corporation should review whether it needs to file Form 1120 for its tax year.
The preparer would first confirm:
- The corporation’s legal status
- Federal tax classification
- Tax year
- EIN
- Whether any special return applies
- Whether there were actually any transactions
- Whether the corporation was dissolved
- Any state filing requirements
This is an illustrative example, not a reported Accounts Confidant client result.
The lesson is simple: “no income” and “no filing requirement” are not automatically the same thing.
Form 1120 Filing Checklist
A final checklist can catch many Form 1120 errors before the return is submitted. Gather the accounting records and supporting documents before beginning the final return review.
Corporation information
- Legal corporate name
- EIN
- Address
- Date incorporated
- Tax year
- Initial, final, or amended-return status, when applicable
- Ownership information
Income records
- Sales and gross receipts
- Interest income
- Dividend income
- Rental income
- Capital gains and losses
- Other income
- Cost of goods sold, when applicable
Expense records
- Payroll and officer compensation
- Rent
- Insurance
- Advertising
- Interest
- Taxes
- Depreciation
- Employee benefits
- Professional fees
- Other business expenses
Tax items
- Prior-year return
- Estimated tax payments
- NOL carryovers
- Applicable credits
- Depreciation schedules
- Research expenses
- Foreign activity information
- Related-party transactions
Final review
Compare:
Bookkeeping → trial balance → financial statements → tax adjustments → Form 1120 → supporting schedules
Keeping these records organized throughout the year makes tax preparation easier. A bank reconciliation process can also help identify missing or incorrectly recorded transactions before the return is prepared.
When Should a Corporation Get Professional Form 1120 Help?
Professional help becomes especially useful when the corporation has multiple shareholders, foreign ownership, related-party transactions, significant deductions, NOLs, international activity, large asset purchases, or complicated book-to-tax differences.
A simple corporation with clean records can still have a filing requirement, but complex transactions can create additional forms and tax calculations.
Professional review can also help identify differences between the accounting records and tax reporting before the return is submitted.
Accounts Confidant provides bookkeeping and accounting support for businesses using third-party accounting software. For businesses that need their financial records prepared and organized before corporate tax filing, bookkeeping help for tax preparation may be relevant.
Final Takeaway
Form 1120 is the main federal income tax return for regular domestic C corporations, and the filing requirement generally exists even when the corporation has no taxable income.
For 2026, the most important points are to confirm the corporation’s tax classification, use the correct tax-year deadline, keep Schedule K questions tied to the corporation’s actual facts, reconcile books and tax reporting through Schedule M-1 or M-3 when required, and review the business tax changes enacted under OBBBA.
One additional point is especially important when searching online: the IRS has released a 2026 draft Form 1120, but it is not a filing document. Use the final IRS form applicable to the corporation’s tax year and check the latest IRS instructions before filing.
IRS Form 1120 FAQ
Do C corporation shareholders receive a Schedule K-1 from Form 1120?
No, A regular C corporation filing Form 1120 does not generally issue Schedule K-1 to shareholders for corporate income. Schedule K-1 is used differently on pass-through returns such as Forms 1120-S and 1065.
Does Form 7004 extend the time to pay Form 1120 tax?
No, Form 7004 generally extends the time to file, not the time to pay. Tax that is due should generally be paid by the original return due date.
Can an inactive corporation skip Form 1120?
Not automatically, a domestic corporation generally has to file an income tax return whether or not it has taxable income, subject to applicable exceptions.
Is the 2026 Form 1120 PDF on the IRS website ready to file?
Not necessarily, The IRS has posted a 2026 draft Form 1120 that is explicitly marked “DRAFT—NOT FOR FILING.” Use the final form applicable to the corporation’s tax year.
Does Form 1120 report state corporate income tax?
No, Form 1120 is a federal corporate income tax return. State and local corporate tax filing requirements are separate and depend on the corporation’s activities and jurisdictions.