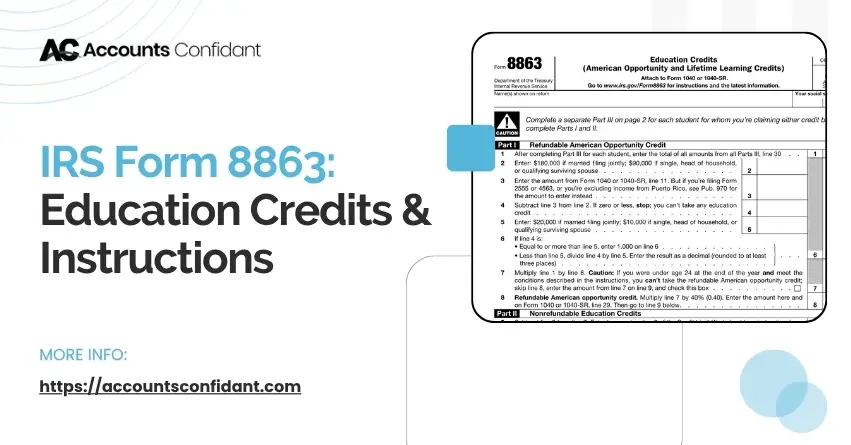
Paying for college, vocational training, or other higher education can be expensive. IRS Form 8863 helps eligible taxpayers claim two federal education tax credits: the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC).
For the 2025 tax year, the AOTC can provide up to $2,500 per eligible student, while the LLC can provide up to $2,000 per tax return. The two credits have different eligibility rules, and you cannot claim both credits for the same student in the same year.
2026 form note: The IRS has released a 2026 draft Form 8863 and draft instructions, but the IRS says draft forms should not be filed. For returns being filed during the 2026 filing season, use the applicable final-year form, currently the 2025 Form 8863.
Official resources: IRS Form 8863 PDF | IRS Form 8863 Instructions
What Is IRS Form 8863?
IRS Form 8863 is the form taxpayers use to calculate and claim the American Opportunity Tax Credit and Lifetime Learning Credit on a federal income tax return. It is generally filed with Form 1040 or Form 1040-SR.
These credits can reduce the federal income tax you owe when you, your spouse, or an eligible dependent has qualified education expenses.
Form 8863 has three main parts:
- Part I: Refundable American Opportunity Credit
- Part II: Nonrefundable Lifetime Learning Credit
- Part III: Student and education expense information used to calculate either credit
The IRS instructs taxpayers to complete Part III separately for each student before completing Parts I and II.
American Opportunity Credit vs. Lifetime Learning Credit
The main difference is that the AOTC is designed mainly for students in their first four years of postsecondary education, while the LLC can apply to undergraduate, graduate, professional, and qualifying job-skill courses without a four-year limit.
| Feature | American Opportunity Tax Credit | Lifetime Learning Credit |
| Maximum credit | Up to $2,500 per eligible student | Up to $2,000 per tax return |
| Refundable | Partially refundable | Nonrefundable |
| Qualified expenses | Tuition, required fees and certain course materials | Qualified tuition and related expenses |
| Enrollment | At least half-time for at least one academic period | One or more courses |
| Education period | First four years of postsecondary education | No limit on number of years |
| Degree/credential | Generally required | Not always required |
| Income limit for 2025 | MAGI below $90,000, or $180,000 joint | MAGI below $90,000, or $180,000 joint |
| Same student | Cannot claim LLC for the same student | Cannot claim AOTC for the same student |
For 2025, the AOTC is calculated using up to $4,000 of qualified expenses: 100% of the first $2,000 and 25% of the next $2,000. The LLC is generally 20% of the first $10,000 of qualifying expenses, for a maximum of $2,000 per return.
Who Can Claim the American Opportunity Credit?
You may qualify for the AOTC if you paid qualified education expenses for yourself, your spouse, or a dependent and the student meets the IRS requirements.
For the 2025 tax year, the student generally must:
- Be enrolled in a program leading to a degree, certificate, or other recognized postsecondary credential.
- Be enrolled at least half-time for at least one academic period beginning during the tax year.
- Be within the first four years of postsecondary education.
- Not have claimed the AOTC for more than four tax years.
- Not have a disqualifying federal or state felony drug conviction.
- Meet the applicable taxpayer identification number requirements.
- Attend an eligible educational institution.
The AOTC is also subject to an income phaseout. For 2025, the MAGI limit is $90,000 for single, head-of-household, or qualifying surviving spouse filers and $180,000 for married couples filing jointly.
Who Can Claim the Lifetime Learning Credit?
The LLC is available when you pay qualified education expenses for yourself, your spouse, or a dependent who attends an eligible educational institution. The student does not have to be in the first four years of college.
The LLC may apply to:
- Undergraduate courses
- Graduate courses
- Professional degree courses
- Courses taken to acquire or improve job skills
- Students taking one or more courses
Unlike the AOTC, there is no limit on the number of tax years you can claim the Lifetime Learning Credit.
The 2025 income limits are also $90,000 for most single filers and $180,000 for married couples filing jointly.
What Education Expenses Qualify for Form 8863?
Qualified expenses generally include tuition and required fees paid for enrollment or attendance at an eligible educational institution. Certain course materials can also qualify for the AOTC.
Expenses that may qualify
Depending on the credit, qualifying expenses can include:
- Tuition
- Required enrollment fees
- Required student fees
- Books required for the course
- Supplies and equipment required for the course, where permitted
- Certain course materials
For the AOTC, required books, supplies, and equipment may qualify even when they are purchased somewhere other than the school.
Expenses that generally do not qualify
Do not assume every college expense belongs on Form 8863. Common nonqualified expenses include:
- Room and board
- Transportation
- Insurance
- Medical expenses
- Student health fees
- Personal living expenses
- Sports or hobby courses, unless an applicable exception applies
- Certain noncredit courses
The IRS also requires qualified expenses to be adjusted for certain scholarships, grants, and other tax-free educational assistance.
Do You Need Form 1098-T for Form 8863?
Usually, yes. The IRS generally requires the taxpayer or dependent to receive Form 1098-T, Tuition Statement, to claim the AOTC or LLC, although specific exceptions apply.
Form 1098-T is normally provided by the eligible educational institution and can help you identify the student’s education expenses.
However, do not simply copy Box 1 of Form 1098-T into Form 8863. The IRS says the amount reported on Form 1098-T can differ from the amount actually paid. Form 8863 should be based on qualified expenses actually paid, after the required adjustments.
If you did not receive Form 1098-T, check whether an exception applies and keep records showing that the student attended an eligible institution and that the qualified expenses were paid.
Can You Claim an Education Credit if the Student Is a Dependent?
Yes, a parent or other taxpayer who claims the student as a dependent may generally claim the education credit for the dependent’s qualified education expenses, assuming all other requirements are met.
A useful rule is that if the student is claimed as a dependent, qualified education expenses paid by the student are generally treated as paid by the person who claims the student as a dependent.
The student generally cannot claim the same education credit on their own return when someone else is entitled to claim the student as a dependent.
How to Fill Out Form 8863
The easiest way to complete Form 8863 is to start with Part III for every student, then complete Part I or Part II based on the credit being claimed.
Step 1: Gather your education records
Before starting Form 8863, collect:
- Form 1098-T
- School payment records
- Tuition statements
- Receipts for qualifying books and supplies
- Scholarship and grant information
- Student Social Security number or applicable TIN
- School information
- Your Form 1040 information
- Information about whether the student is your dependent
This makes it easier to determine the actual amount of qualified expenses.
Step 2: Complete Part III for each student
Part III asks for information about the student and educational institution.
You generally need to provide:
- Student’s name
- Student’s taxpayer identification number
- School information
- School EIN when required for the AOTC
- Form 1098-T information
- Enrollment information
- Whether the student completed the first four years of postsecondary education
- Prior AOTC claims
- Qualified education expenses
If you are claiming a credit for more than one student, complete a separate Part III for each student.
Step 3: Complete Part I for the American Opportunity Credit
Part I is used to calculate the refundable portion of the AOTC.
For 2025, the maximum AOTC is $2,500 per eligible student. Up to 40% of the allowed credit, generally a maximum of $1,000, may be refundable.
The calculation also takes your income and other tax-credit limitations into account.
Step 4: Complete Part II for the Lifetime Learning Credit
Part II is used to calculate the LLC.
The credit is generally 20% of the first $10,000 of qualifying education expenses, making the maximum $2,000 per return. The LLC is nonrefundable, so it can reduce your tax liability but does not generally create a refund by itself when it exceeds your tax liability.
Step 5: Transfer the credit to your tax return
Form 8863 does not stand alone. The completed form is attached to your federal tax return.
For the AOTC, the nonrefundable portion is reported through Schedule 3, while the refundable portion is reported on Form 1040 or Form 1040-SR. The LLC is reported through Schedule 3.
Form 8863 Income Limits
The income limits determine whether your education credit is reduced or unavailable. For 2025, both the AOTC and LLC use a $90,000 MAGI threshold for single, head-of-household, and qualifying surviving spouse filers and $180,000 for married filing jointly.
The credit does not simply disappear at the first dollar above the threshold. The IRS rules provide for a phaseout over the applicable income range.
Because MAGI calculations can be affected by specific tax items, use the applicable Form 8863 instructions rather than relying only on your gross income.
Can You Claim Both Education Credits?
Yes, but not for the same student in the same year. A taxpayer with multiple eligible students may use different credits for different students when the requirements are met.
For example:
- Student A qualifies for the AOTC.
- Student B qualifies for the LLC.
The same taxpayer may potentially claim both credits on one return, but the same student cannot be used to claim both credits.
You also cannot use the same expenses to obtain two federal tax benefits.
Form 8863 PDF: Where to Get the Form
The safest place to get a blank Form 8863 PDF is the IRS website.
The IRS also provides the official instructions explaining eligibility, qualified expenses, income limits, and the line-by-line calculation.
Important: The IRS currently lists a 2026 Form 8863 as a draft version. The IRS specifically warns taxpayers not to file draft forms.
If you are preparing a 2026 tax return for expenses paid during 2026, check the IRS Form 8863 page for the final 2026 version when it is released.
Common Form 8863 Mistakes to Avoid
Most Form 8863 problems come from eligibility or expense errors rather than the form itself.
Using the wrong tax-year form
Forms change by tax year. Always make sure the form matches the tax year of the return.
Treating Form 1098-T Box 1 as the final expense amount
Box 1 can help you start the calculation, but the amount you actually paid and the required adjustments matter.
Claiming both credits for one student
You cannot claim both the AOTC and LLC for the same student in the same year.
Including room and board
Room and board is generally not a qualified expense for these credits.
Ignoring scholarships and grants
Tax-free educational assistance can reduce the expenses that are available for calculating the credit.
Forgetting the student limit for AOTC
The AOTC has specific rules involving the first four years of postsecondary education and prior AOTC claims.
Using the same expenses for another tax benefit
The IRS does not allow the same expenses to be used for overlapping federal education tax benefits in a way that creates a double benefit.
Form 8863 Example: A Student and a Parent
Consider a simple example.
This is an illustrative example, not a tax calculation for a specific taxpayer.
Maria’s daughter is an eligible dependent who attends college. Maria paid qualifying tuition and required course expenses during the tax year. Her daughter is enrolled at least half-time and is still within the first four years of postsecondary education.
Maria reviews the Form 1098-T and her payment records, adjusts the expenses for scholarships and other required adjustments, and completes Part III for her daughter.
Because the student meets the AOTC requirements, Maria calculates the AOTC in Part I rather than claiming the LLC for the same student.
The important point is that the choice of credit comes after checking eligibility and calculating adjusted qualified expenses. A taxpayer should not select a credit only because its maximum amount looks larger.
What Happens If Your Education Credit Was Previously Denied?
If the IRS previously denied or reduced your AOTC for a reason other than a mathematical or clerical error, you may need to file Form 8862 before claiming the credit again. The 2025 Form 8863 instructions specifically address this requirement.
If you are correcting an already-filed return, you may also need Form 1040-X.
You can read our related guide on How to File Form 1040-X for information about amended federal tax returns.
Form 8863 and E-Filing
Yes, Form 8863 can generally be filed electronically as part of an eligible federal tax return. The form is attached to Form 1040 or Form 1040-SR when claiming an education credit.
Tax software normally asks questions about the student’s education expenses and eligibility and then generates Form 8863 when appropriate.
If you prepare the return manually, follow the current IRS form and instructions carefully.
Final Takeaway
IRS Form 8863 is the key form for claiming the American Opportunity Tax Credit or Lifetime Learning Credit. The most important steps are to confirm eligibility, identify the correct credit, calculate qualified expenses, account for scholarships and other adjustments, and complete Part III for each student before calculating the credit.
For the 2025 tax year, the AOTC can be worth up to $2,500 per eligible student, while the LLC can be worth up to $2,000 per return.
For additional tax-form guidance, you can also explore Accounts Confidant’s articles on Form 1040-X and amended returns, IRS Form 2848, and IRS Form 8949.
If your education expenses involve scholarships, multiple students, dependency issues, or a previously denied credit, review the current IRS instructions carefully before filing.
Frequently Asked Questions About IRS Form 8863
What is IRS Form 8863?
IRS Form 8863 is used to calculate and claim the American Opportunity Tax Credit and Lifetime Learning Credit.
Who can claim the American Opportunity Credit?
A taxpayer may qualify when paying qualified education expenses for an eligible student who meets the AOTC requirements, including the first-four-years and at-least-half-time rules.
Who can claim the Lifetime Learning Credit?
A taxpayer may qualify when paying qualified education expenses for themselves, their spouse, or a dependent attending an eligible institution. The LLC can apply to undergraduate, graduate, professional, and qualifying job-skill courses.
What is the difference between the American Opportunity Credit and Lifetime Learning Credit?
The AOTC can provide up to $2,500 per eligible student and is partially refundable. The LLC can provide up to $2,000 per return and is nonrefundable. Their student and education requirements are also different.
How do I fill out Form 8863?
Start with Part III for each student. Then complete Part I for the AOTC or Part II for the LLC, apply the income and credit limits, and transfer the result to your federal return.
What expenses qualify for education credits on Form 8863?
Generally, qualified tuition and required fees qualify. For the AOTC, certain required books, supplies, and equipment can also qualify. Room and board, transportation, insurance, and most personal expenses do not qualify.
Do I need Form 1098-T to file Form 8863?
Generally, yes, but the IRS provides exceptions in specific situations. If you do not receive Form 1098-T, review the IRS rules before claiming the credit.
Can I claim education credits if I’m claimed as a dependent?
Generally, a person claimed as someone else’s dependent cannot claim the education credit for themselves. The person claiming the dependent may generally claim the eligible education credit instead.
Can I e-file Form 8863?
Yes, Form 8863 is generally included electronically with an eligible federal income tax return when the tax software supports the credit.
What are the income limits for education credits?
For 2025, the MAGI threshold is $90,000 for single, head-of-household, or qualifying surviving spouse filers and $180,000 for married filing jointly. A phaseout can apply.
Can I claim both credits on the same return?
Yes, if the credits apply to different students and the other requirements are met. You cannot claim both credits for the same student.
What are common mistakes on Form 8863?
Common mistakes include using the wrong tax-year form, entering expenses that do not qualify, ignoring scholarships or grants, copying Form 1098-T amounts without checking actual payments, and claiming both credits for the same student.