Losing a family member often leaves survivors with many financial and tax responsibilities. If the deceased taxpayer was owed a federal income tax refund, the IRS has specific rules for determining who can claim that money.
IRS Form 1310, Statement of Person Claiming Refund Due a Deceased Taxpayer, is used in certain situations to claim a refund on behalf of someone who has died. However, not every surviving spouse, executor, or personal representative needs to file it.
The most important question is who is claiming the refund and how the refund is being claimed.
For example, a surviving spouse filing an original or amended joint return generally does not file Form 1310. Likewise, a court-appointed personal representative filing the deceased person’s original Form 1040 generally does not need Form 1310 if the required court certificate is attached to the return.
This guide explains IRS Form 1310 instructions 2026, who must file, the rules for a Form 1310 surviving spouse, how to complete each section, where to send the form, electronic filing rules, processing considerations, and common mistakes.
Current form note: The IRS currently provides Form 1310 with a December 2025 revision. Check the official IRS Form 1310 page for any later revision before filing.
What Is IRS Form 1310?
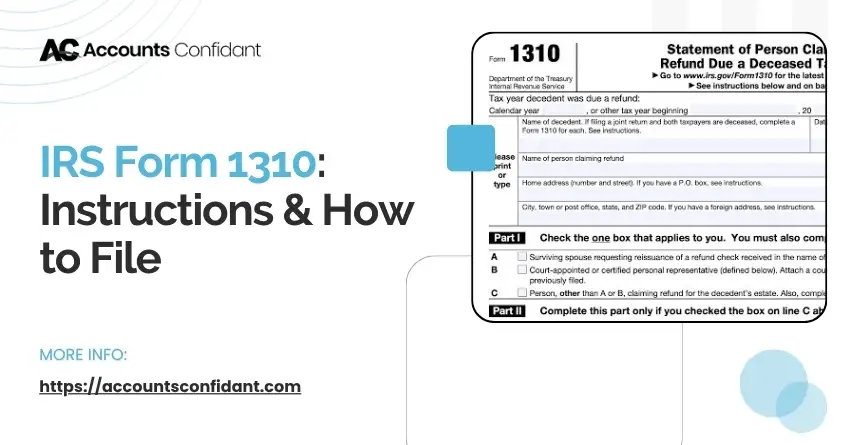
IRS Form 1310 is used to claim a federal tax refund that is owed to a deceased taxpayer when the person claiming the refund falls into one of the situations covered by the form.
The form is titled:
Statement of Person Claiming Refund Due a Deceased Taxpayer
It asks for information such as:
- Name of the deceased taxpayer
- Date of death
- Deceased taxpayer’s Social Security number
- Name of the person claiming the refund
- Claimant’s Social Security number
- Claimant’s address
- Relationship or legal status relevant to the claim
- Signature and date
Form 1310 does not replace the deceased person’s final tax return.
Instead, it supports a refund claim when the person requesting the refund needs to establish that they are entitled to receive it.
The IRS explains that the final tax return of a deceased person is generally prepared much like the return would have been prepared while the person was alive, with income through the date of death reported.
Who Needs to File Form 1310?
You generally need Form 1310 when you are claiming a refund for a deceased taxpayer, and your situation falls under Part I, line A, B, or C of the form.
The current form has three categories.
Line A — Surviving Spouse Reissuing a Joint Refund Check
Use line A when you are the surviving spouse and you received a refund check made payable to both you and your deceased spouse.
The form allows you to request that the joint-name check be reissued in your name.
Line B — Court-Appointed or Certified Personal Representative
Line B applies to a court-appointed or certified personal representative claiming a refund on Form 1040-X or Form 843.
Under the current Form 1310 instructions, the representative must attach a copy of the court certificate showing the appointment, even if the certificate was previously sent to the IRS.
Line C — Other Person Claiming the Estate Refund
Line C applies when someone other than the surviving spouse in line A or a court-appointed/certified personal representative in line B is claiming the refund for the deceased person’s estate.
Part II must also be completed when line C is selected.
When Is Form 1310 Required?
Form 1310 is required when the person claiming the refund fits one of the categories identified in the form’s Part I.
A common situation involves a deceased taxpayer who was entitled to a refund but did not have a surviving spouse filing a joint return or a court-appointed personal representative filing the original return with the required court certificate.
For example:
A taxpayer dies before filing a tax return. No personal representative has been appointed, and a family member is responsible for the deceased person’s property. The final return shows a $2,000 refund.
The person claiming the refund may need to complete Form 1310 under line C and answer the Part II questions.
Important Point
The existence of a refund does not automatically mean Form 1310 is required.
The IRS specifically lists situations where Form 1310 should not be filed.
When You Do Not Need Form 1310
A surviving spouse filing an original or amended joint return with the deceased taxpayer generally does not need Form 1310. A court-appointed personal representative filing the deceased person’s original return also generally does not need it when the required court certificate is attached.
There are two key exceptions.
Surviving Spouse Filing a Joint Return
If you are the surviving spouse filing an original or amended joint return with the deceased taxpayer, Form 1310 generally is not required.
The surviving spouse generally signs the joint return and indicates that they are filing as the surviving spouse.
Court-Appointed Personal Representative Filing the Original Return
A court-appointed or certified personal representative filing the deceased person’s original Form 1040, 1040-SR, 1040-NR, or 1040-SS generally does not need Form 1310 when a copy of the court certificate showing the appointment is attached to the return.
This distinction is important because a personal representative filing an amended return can have a different Form 1310 requirement.
Can a Surviving Spouse File Form 1310?
Yes, but a surviving spouse does not generally use Form 1310 when filing an original or amended joint return with the deceased spouse.
A surviving spouse may need Form 1310 in a different situation: when a refund check was issued in both spouses’ names and the surviving spouse wants the IRS to reissue the check in the survivor’s name alone.
Example
John and Mary filed a joint return.
John later dies.
The IRS sends a refund check payable to:
John and Mary Smith
Mary wants the refund check reissued in her name.
Mary can use Form 1310, line A, and return the joint-name check as instructed by the IRS.
This is different from filing the final joint tax return itself.
Form 1310 Instructions 2026
The current Form 1310 instructions explain three claimant categories, the information required from each claimant, and the documents needed to support the refund claim.
The current IRS form is Form 1310, Rev. December 2025.
Before completing the form, gather:
- Deceased taxpayer’s full name
- Date of death
- Deceased taxpayer’s SSN
- Your full name
- Your SSN
- Your current address
- Copy of the final tax return
- Refund information
- Court appointment documents, if applicable
- Proof of death, when required
- Joint refund check, if requesting reissuance
Keep the Original Records
The IRS may request supporting documentation.
For a line C claim, the current instructions say you must have proof of death, such as a death certificate or formal notification from an appropriate government office, but you should keep it for your records rather than attach it to Form 1310 unless the IRS requests it.
How to Fill Out Form 1310
Form 1310 is relatively short, but choosing the correct Part I category and providing the required supporting documents are critical.
The form contains three main parts.
Step 1: Enter the Taxpayer and Claimant Information
Start by entering the deceased taxpayer’s information and the information of the person claiming the refund.
You generally enter:
- Tax year for which the refund is due
- Decedent’s name
- Date of death
- Decedent’s SSN
- Claimant’s name
- Claimant’s SSN
- Claimant’s mailing address
Make sure the names and Social Security numbers match the tax records.
An incorrect SSN or taxpayer name can cause processing problems.
Form 1310 Part I: Choose the Correct Box
Part I is the most important section because it determines why you are entitled to claim the refund.
The current form says to check only one box.
Box A: Surviving Spouse
Choose A if you are the surviving spouse requesting reissuance of a refund check issued in both spouses’ names.
You should have the original joint-name refund check available.
The IRS instructions state that the check can be marked “VOID” and returned with Form 1310 and a written request for reissuance.
Do not use line A simply because your spouse died and a refund is due.
The line A situation specifically concerns a joint-name refund check.
Box B: Personal Representative
Choose B if you are the deceased taxpayer’s court-appointed or certified personal representative claiming a refund on Form 1040-X or Form 843.
The current form requires the court certificate showing your appointment to be attached.
This requirement applies even if the certificate was previously provided to the IRS.
Box C: Other Person Claiming the Estate Refund
Choose C when you are claiming the refund for the deceased taxpayer’s estate and you are not covered by line A or line B.
You must also complete Part II.
The IRS requires proof of death for a line C claim, although the instructions say to keep that proof and provide it if requested rather than attaching it automatically.
Form 1310 Part II: Estate Questions
Part II is completed only when you select line C in Part I.
The section asks three questions.
Question 1: Did the Decedent Leave a Will?
Answer Yes or No based on the deceased person’s estate documents.
Question 2: Has a Court Appointed a Personal Representative?
You must answer whether a court has appointed a personal representative.
If not, the form also asks whether one will be appointed.
The IRS states that if a personal representative has been or will be appointed, that personal representative must file for the refund.
Question 3: Will You Pay the Refund According to State Law?
This question asks whether you will distribute the refund according to the laws of the state where the deceased taxpayer was legally resident.
If you answer No, the IRS says the refund cannot be made until you provide a court certificate showing your appointment as personal representative or other evidence that you are legally entitled to receive the refund.
Form 1310 Part III: Signature and Verification
Every person filing Form 1310 must complete Part III.
You must:
- Sign the form
- Enter the date
- Provide a phone number if desired
The phone number is optional.
By signing, you are declaring under penalties of perjury that the information is true, correct, and complete to the best of your knowledge.
Do not leave the signature section blank.
An unsigned form can create a processing problem.
What Documents Do You Need for Form 1310?
The documents needed depend on why you are filing Form 1310.
If You Are a Surviving Spouse Using Line A
You generally need:
- Form 1310
- Joint-name refund check
- Written request for reissuance
The IRS says the joint-name check should be marked “VOID” before being returned.
If You Are a Personal Representative Using Line B
You need:
- Form 1310
- Court certificate showing your appointment
The current instructions specifically require the court certificate to be attached even if the IRS received it previously.
If You Are Claiming Under Line C
You should have:
- Form 1310
- Final tax return
- Proof of death
- Estate records
- Information showing your entitlement to the refund
The current instructions say to keep proof of death and provide it if the IRS requests it.
Where Do You Mail Form 1310?
The correct mailing location depends on how Form 1310 is being filed and which tax return it accompanies.
For line B or line C claims, the IRS instructs taxpayers to follow the filing instructions for the form to which Form 1310 is attached. If Form 1310 is filed separately, it generally goes to the same IRS service center where the original return was filed.
If the original return was filed electronically, the IRS provides a designated service center based on the claimant’s address and the instructions for the original return.
For Line A
If you are requesting reissuance of a joint-name refund check, the IRS says you can return the check and Form 1310 to your local IRS office or the IRS service center where you filed your return.
Because IRS mailing addresses can change, use the current IRS instructions rather than an old address from another website.
Can I E-File Form 1310?
Yes, Form 1310 can be electronically filed in certain situations when it is attached to an electronically filed Form 1040, 1040-SR, 1040-NR, or 1040-SS.
This does not mean every Form 1310 situation is handled electronically.
The filing method depends on the type of claim.
If Form 1310 is filed separately, the current instructions direct taxpayers to mail it to the appropriate IRS service center.
Electronic Filing Example
Suppose a person is filing a deceased taxpayer’s Form 1040 electronically and Form 1310 is required.
The tax software may allow Form 1310 to be included with the electronic return.
The IRS confirms that Form 1310 can be filed electronically when attached to an electronically filed Form 1040, 1040-SR, 1040-NR, or 1040-SS.
Form 1310 Processing Time
The IRS does not publish a single guaranteed processing time specifically for Form 1310.
A refund involving a deceased taxpayer can require additional review because the IRS must establish who is legally entitled to receive the money.
Processing can depend on:
- Whether the return is complete
- Whether Form 1310 is required
- Whether supporting documents are complete
- Whether the claim is electronically filed or mailed
- Whether the IRS needs additional information
- Whether the return is selected for review
- Whether the refund has already been issued
- Whether the claim involves an amended return
The IRS’s internal guidance recognizes that Form 1310 can require special handling when tracing or reissuing a refund.
How to Avoid Unnecessary Delays
Make sure:
- Names are correct
- SSNs are correct
- The correct Part I box is selected
- Part II is complete when required
- The form is signed
- Required court documentation is attached
- The refund check is handled correctly
- You use the correct IRS filing location
If the IRS requests additional information, respond promptly.
Form 1310 vs. Form 1040
Form 1040 reports the deceased taxpayer’s income and calculates the tax or refund, while Form 1310 establishes the claimant’s eligibility to receive a refund in situations covered by the form.
| Form | Main purpose |
| Form 1040 | Reports the taxpayer’s income, deductions, credits, tax, and refund or balance due |
| Form 1310 | Identifies the person claiming a refund due to a deceased taxpayer |
| Form 1040-X | Corrects an already filed individual tax return |
| Form 843 | Claims certain refunds or requests abatement of specific taxes |
A final Form 1040 is generally still required when the deceased taxpayer had a filing requirement. Form 1310 does not replace it.
For an amended return, the IRS specifically states that a court-appointed personal representative or other person claiming a refund should file Form 1040-X and attach Form 1310 when applicable.
What Happens If You Don’t File Form 1310?
If Form 1310 is required but is missing, the IRS may not be able to release the refund to the person claiming it.
The IRS uses Form 1310 to determine whether the claimant is eligible to receive the deceased taxpayer’s refund.
Missing information can delay or prevent processing.
The current form specifically states that failure to provide required information may delay or prevent processing of the claim.
If you discover that Form 1310 was omitted, review the filing instructions for the applicable return and determine whether a corrected submission or additional documentation is required.
Common Form 1310 Mistakes
Most Form 1310 problems can be avoided by choosing the correct claimant category and providing the documentation required for that category.
Choosing Line C When a Personal Representative Exists
If a court has appointed a personal representative, the person claiming the refund generally cannot simply use line C instead.
The current instructions state that if a personal representative has been or will be appointed, the personal representative must file for the refund.
Filing Form 1310 When a Surviving Spouse Does Not Need It
A surviving spouse filing an original or amended joint return generally does not need Form 1310.
Check the filing situation before adding the form.
Forgetting the Court Certificate
A line B filer must attach the court certificate showing the appointment under the current instructions, even if it was previously submitted to the IRS.
Attaching the Death Certificate Automatically
For a line C claim, the IRS instructions say to keep proof of death and provide it if requested. It should not automatically be attached to Form 1310.
Leaving Part II Blank
Part II is required when line C is selected.
Skipping these questions can make the claim incomplete.
Forgetting the Signature
All Form 1310 filers must complete Part III and sign the form.
Using an Old Form
IRS forms are periodically revised.
Use the current version available on the IRS website rather than relying on an old Form 1310 PDF.
Case Study: A Parent Dies Without a Court-Appointed Representative
This is an illustrative example, not a real client case.
Suppose a taxpayer dies during the year.
The taxpayer:
- Was not married at the time of death
- Did not have a court-appointed personal representative
- Had no appointed executor
- Was entitled to a $1,500 federal income tax refund
- Left a will
- Had an adult child handling the deceased person’s property
The adult child wants to claim the refund.
Step 1: Determine Whether Form 1310 Applies
The child is not a surviving spouse and is not a court-appointed personal representative.
The claim may therefore fall under Part I, line C.
Step 2: Complete Part II
Because line C is selected, the child must answer the questions concerning:
- Whether the taxpayer left a will
- Whether a personal representative has been appointed or will be appointed
- Whether the refund will be distributed according to applicable state law
Step 3: Keep Proof of Death
The child should keep a copy of the death certificate.
The current Form 1310 instructions state that proof of death is required for a line C claim but should be retained and provided if the IRS requests it.
Step 4: Sign Form 1310
The child completes Part III and signs the form.
Step 5: File With the Appropriate Return
The Form 1310 is attached or filed according to the applicable IRS instructions.
The important point is that the person who receives the refund must have a valid basis for claiming it. Being a family member alone does not automatically establish the right to the refund.
Form 1310 Filing Checklist
Use this checklist before submitting a Form 1310 claim.
- Confirm that the deceased taxpayer is owed a refund.
- Determine who is legally claiming the refund.
- Check whether Form 1310 is actually required.
- Enter the correct tax year.
- Enter the decedent’s full name.
- Enter the date of death.
- Enter the decedent’s SSN.
- Enter the claimant’s information.
- Select only one Part I box.
- Complete Part II if line C is selected.
- Attach the court certificate if line B applies.
- Keep proof of death if line C applies.
- Complete and sign Part III.
- Follow the applicable IRS mailing or e-filing instructions.
- Keep a complete copy of the form and supporting records.
Final Takeaway
IRS Form 1310 helps the IRS determine who is entitled to receive a federal tax refund owed to a deceased taxpayer in specific situations.
The key rules are:
- Surviving spouse filing a joint return: Form 1310 generally is not required.
- Joint-name refund check: A surviving spouse can use line A to request reissuance in the survivor’s name.
- Court-appointed representative filing the original return: Form 1310 generally is not required when the required court certificate is attached.
- Representative filing Form 1040-X or Form 843: Form 1310 and the court certificate are required under the current instructions.
- Other person claiming the estate refund: Line C and Part II may apply.
- Proof of death: Required for line C, but generally kept in your records unless the IRS requests it.
- Electronic filing: Available in certain situations when Form 1310 is attached to an eligible electronically filed return.
The current IRS Form 1310 is Rev. December 2025, and the IRS directs taxpayers to its Form 1310 page for later developments.
Frequently Asked Questions
What is IRS Form 1310?
IRS Form 1310 is the Statement of Person Claiming Refund Due a Deceased Taxpayer. It is used in specified situations to claim or obtain a refund owed to someone who has died.
Who needs to file Form 1310?
A person generally files Form 1310 when their situation falls under Part I, line A, B, or C.
When is Form 1310 required?
It is generally required when someone other than an exempt surviving spouse or qualifying personal representative is claiming a deceased taxpayer’s refund, or when one of the specific Part I situations applies.
Can a surviving spouse file Form 1310?
Yes, A surviving spouse can use Form 1310 in certain situations, such as requesting reissuance of a refund check made payable to both spouses. A surviving spouse filing an original or amended joint return generally does not need Form 1310.
Do I need Form 1310 if I file a joint return?
Generally, no. A surviving spouse filing an original or amended joint return with the deceased spouse does not generally file Form 1310.
What is the difference between Form 1310 and Form 1040?
Form 1040 reports the deceased taxpayer’s income and calculates the tax. Form 1310 establishes information about the person claiming the refund when the form is required.
How do I fill out Form 1310?
Enter the decedent’s information, claimant information, select the appropriate Part I category, complete Part II if line C applies, and sign Part III.
Where do I mail Form 1310?
The mailing address depends on how Form 1310 is being filed and which return it accompanies. Follow the current IRS instructions for the related return rather than using a general address.
How long does it take to get a refund with Form 1310?
There is no single IRS-published processing time specifically for Form 1310. Claims involving deceased taxpayers may require additional review, so processing can vary.
What happens if I don’t file Form 1310?
If Form 1310 is required and is missing, the IRS may delay or be unable to process the refund claim.
Can I e-file Form 1310?
Yes, in certain situations. The IRS allows Form 1310 to be electronically filed when attached to an electronically filed Form 1040, 1040-SR, 1040-NR, or 1040-SS.
What are common mistakes on Form 1310?
Common mistakes include selecting the wrong Part I box, filing the form when it is not required, failing to attach a required court certificate, leaving Part II incomplete, and forgetting to sign the form.